Working Capital Loans for Startups: 2026 Guide
Discover how working capital loans for startups can fuel growth, bridge cash-flow gaps, and support early-stage businesses in 2026.
Starting a business requires more than a great idea. It demands capital to cover daily operations, inventory, payroll, and the inevitable gaps between receivables and payables. For early-stage companies, working capital loans for startups offer a critical funding mechanism to bridge these gaps and maintain momentum during periods when cash flow is unpredictable. Understanding the landscape of startup working capital financing in 2026 means navigating evolving lender criteria, alternative funding options, and strategic cash management practices that can determine whether a young company thrives or stalls.
Understanding Working Capital Loans for Startups
Working capital loans represent short-term financing designed to fund a company's everyday operations rather than long-term asset acquisition or expansion. For startups, these loans address the unique challenge of maintaining liquidity when revenue is inconsistent or growth demands outpace incoming cash.
What Qualifies as Working Capital
Working capital is the difference between current assets and current liabilities. It measures a company's ability to meet short-term obligations. Startups typically use working capital financing for:
- Inventory purchases when preparing for peak seasons or scaling production
- Payroll coverage during revenue gaps or extended payment cycles
- Marketing campaigns that require upfront investment before returns materialize
- Accounts receivable gaps when clients delay payments but expenses continue
- Emergency repairs or unexpected operational costs that cannot wait
These expenses are operational, not capital expenditures. The financing is meant to keep the business running smoothly, not to buy equipment or real estate.
How Startup Working Capital Differs
According to the 2024 Small Business Credit Survey on startup firms, newer businesses face distinct challenges when seeking financing. Startups typically lack the credit history, collateral, and consistent revenue streams that traditional lenders prefer. The survey found that 42% of startup applicants received less funding than requested, and many turned to personal financing or alternative lenders to fill the gap.
This creates a different financing landscape where revenue trends, founder creditworthiness, and business model viability often matter more than traditional balance-sheet metrics. Lenders evaluate startups on potential rather than proven performance, which changes the underwriting criteria substantially.
Types of Working Capital Financing Available
Startups have access to several working capital loan structures, each with distinct advantages and qualification requirements.
| Financing Type | Best For | Typical Terms | Key Consideration |
|---|---|---|---|
| SBA 7(a) Working Capital Pilot | Businesses with SBA-eligible purposes | Up to $5 million, 10-year max | Requires strong credit, collateral |
| Business Line of Credit | Recurring, variable expenses | Revolving access, 12-36 months | Draw only what you need |
| Revenue-Based Financing | Businesses with consistent sales | 3-18 months, % of revenue | Repayment flexes with revenue |
| Term Loans | Predictable, lump-sum needs | Fixed payments, 6-60 months | Requires regular cash flow |
| Merchant Cash Advance | Credit card sales volume | 3-12 months, daily/weekly payments | Higher cost, fast access |
SBA-Backed Working Capital Options
The Small Business Administration offers several programs that can fund working capital needs. The SBA 7(a) loan program includes a working capital pilot initiative designed specifically for short-term operational financing. These loans carry government guarantees that reduce lender risk, often resulting in better terms for qualified borrowers.
SBA loans require substantial documentation, including business plans, financial projections, and personal guarantees. Processing times can extend several weeks, making them less suitable for urgent funding needs but valuable for planned growth phases.
Lines of Credit for Flexible Access
A business line of credit provides revolving access to capital up to a predetermined limit. Startups draw funds as needed and pay interest only on the outstanding balance. This structure suits businesses with variable working capital requirements or seasonal fluctuations.
Credit lines require regular renewals and may include maintenance fees or minimum draw requirements. Lenders typically evaluate revenue consistency and credit profile when setting limits and interest rates.
Alternative Financing Solutions
When traditional loans prove inaccessible, startups increasingly turn to alternative funding. Revenue-based financing and merchant cash advances prioritize business performance over credit history. These products advance capital in exchange for a percentage of future sales or receivables.
The FDIC's 2024 Small Business Lending Survey documented growing competition among non-bank lenders serving early-stage companies. Alternative lenders often approve funding faster and with fewer documentation requirements, though at higher effective costs than traditional loans.
Qualifying for Working Capital Loans as a Startup
Lender criteria for working capital loans for startups have evolved considerably. While traditional banks remain cautious, the broader financing ecosystem offers pathways for businesses at various stages.
Revenue and Time in Business
Most working capital lenders establish minimum thresholds:
- Monthly revenue: $10,000–$25,000 minimum (varies by lender and product)
- Time in business: 6–12 months of operational history
- Cash flow: Demonstrated ability to service debt payments
Startups below these thresholds may need to explore founder-backed financing, equity investment, or secured lending options where collateral mitigates the risk.
Credit Profile Requirements
Both business and personal credit factor into approval decisions. Many lenders require:
- Personal credit scores of 600–650 minimum (higher for favorable terms)
- No recent bankruptcies or major derogatory marks
- Business credit profile (if established) without serious delinquencies
Some alternative lenders focus primarily on bank statements and revenue trends, minimizing credit score weight in their underwriting models.
Documentation and Financial Records
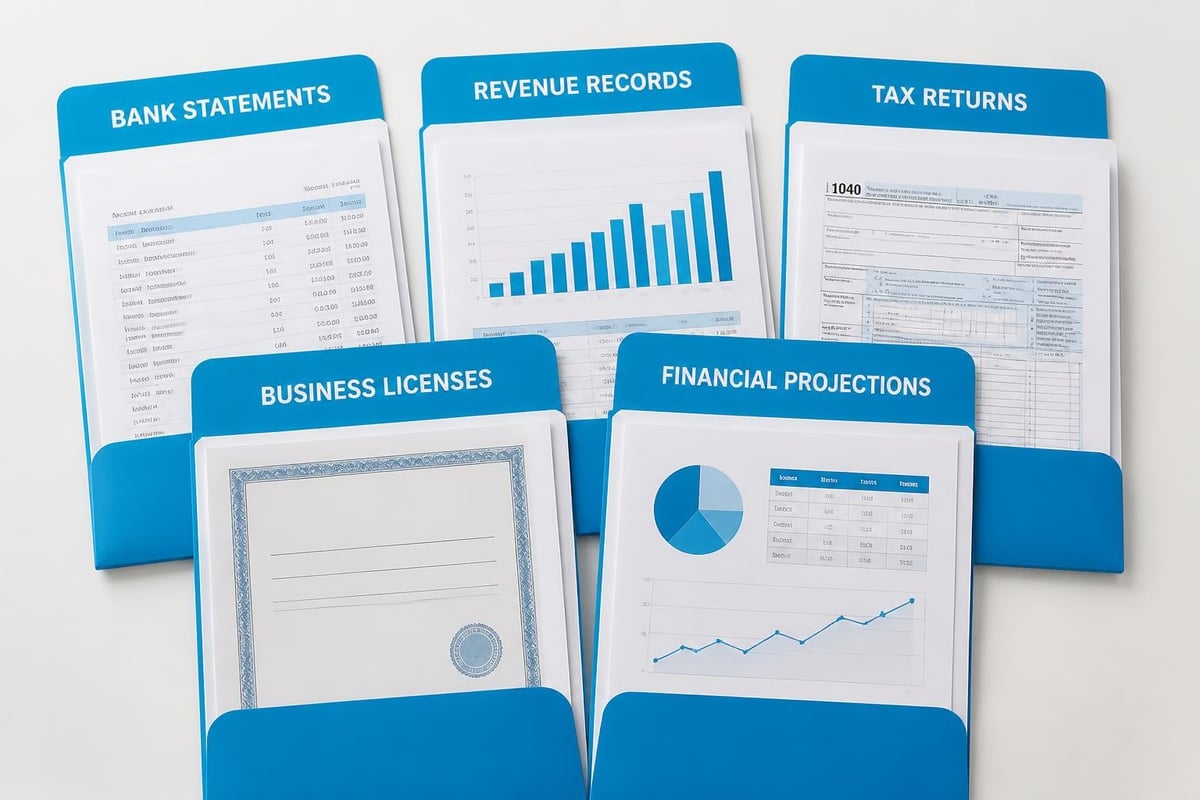
Preparation significantly improves approval odds. Startups should organize:
- Bank statements covering 3–6 months of business activity
- Tax returns (business and personal) for the most recent year
- Profit and loss statements and balance sheets
- Accounts receivable aging reports if applicable
- Business plan or growth projections for substantial requests
The IRS Publication 583 provides guidance on recordkeeping requirements for startups, which directly supports the documentation process for financing applications.
Strategic Uses of Working Capital for Early-Stage Growth
Working capital loans for startups deliver maximum value when deployed strategically rather than reactively. Smart allocation accelerates growth while maintaining financial discipline.
Inventory and Supply Chain Management
Product-based startups often face inventory financing challenges. Purchasing stock requires upfront capital, but sales may take weeks or months to materialize. Working capital financing can:
- Bridge seasonal demand by funding inventory purchases before peak selling periods
- Secure bulk discounts from suppliers when paying in advance
- Prevent stockouts that result in lost sales and customer dissatisfaction
- Support product launches requiring initial manufacturing runs
Careful inventory planning ensures borrowed capital generates returns that exceed financing costs.
Payroll and Talent Acquisition
Access to skilled talent can determine startup success. Working capital enables companies to:
- Hire key employees before revenue fully supports expanded payroll
- Meet payroll obligations during temporary revenue dips
- Offer competitive compensation packages that attract top candidates
- Invest in training and development that builds long-term value
As noted in Harvard Business Review's analysis of building startups in tough funding environments, preserving operational capacity during lean periods often separates companies that survive from those that fail.
Marketing and Customer Acquisition
Revenue growth requires customer acquisition, which demands upfront investment. Working capital can fund:
- Digital advertising campaigns with measurable ROI
- Trade show participation and event marketing
- Content creation and SEO development
- Sales team expansion and commission structures
The key is ensuring customer acquisition cost (CAC) remains below customer lifetime value (LTV), so borrowed capital generates profitable growth.
Managing Costs and Terms
Understanding the true cost of working capital loans for startups prevents expensive mistakes. Interest rates tell only part of the story.
Comparing Effective Rates
Different financing structures calculate costs differently:
| Cost Metric | What It Measures | Why It Matters |
|---|---|---|
| Annual Percentage Rate (APR) | Annualized cost including fees | Standard comparison across products |
| Factor Rate | Total repayment as multiple of advance | Common in MCAs; must convert to APR |
| Cents on the Dollar | Daily or weekly collection amount | Affects cash flow impact |
| Origination Fees | Upfront costs to obtain funding | Reduces net proceeds |
A merchant cash advance with a 1.3 factor rate may appear reasonable until converted to an effective APR exceeding 40%. Transparency in cost calculations enables informed decisions.
Repayment Structures and Cash Flow Impact
Repayment terms directly affect operational cash flow:
- Daily or weekly payments (common in MCAs and some short-term loans) create constant cash outflow
- Monthly payments align better with most business cycles but require discipline in cash management
- Revenue-based repayment adjusts to sales fluctuations, providing downside protection
- Interest-only periods preserve cash initially but increase total cost
Startups should model repayment scenarios against projected cash flow to ensure obligations remain manageable during slower periods.
Early Repayment Considerations
Some lenders charge prepayment penalties that eliminate the benefit of early payoff. Others use Rule of 78s or similar structures that front-load interest. Reading terms carefully and asking specific questions about early repayment reveals the true flexibility of each financing option.
Regulatory and Compliance Considerations
The regulatory landscape for small-business lending continues to evolve. The Consumer Financial Protection Bureau's small business lending resources detail recent rule changes affecting disclosure requirements and data reporting.
Truth in Lending and Disclosure Requirements
In 2026, enhanced disclosure rules require many lenders to provide standardized cost information, including APR and total payment amounts. These protections help startups compare options accurately, though not all lenders fall under these requirements.
State Lending Regulations
Working capital lending is subject to state-level regulation that varies significantly. Some states cap interest rates or impose licensing requirements on certain lender types. Startups should verify that prospective lenders operate legally in their jurisdiction and understand the protections available.
Tax Implications of Borrowed Capital
Working capital loans create tax considerations distinct from equity financing. Loan proceeds are not taxable income, but interest payments may be deductible as business expenses. Proper documentation of how funds are used supports these deductions. The IRS guidance for startups provides essential background on business expense categorization.
Alternatives and Complementary Strategies
Working capital loans for startups represent one tool among several for managing liquidity and funding growth.
Equity Financing vs. Debt
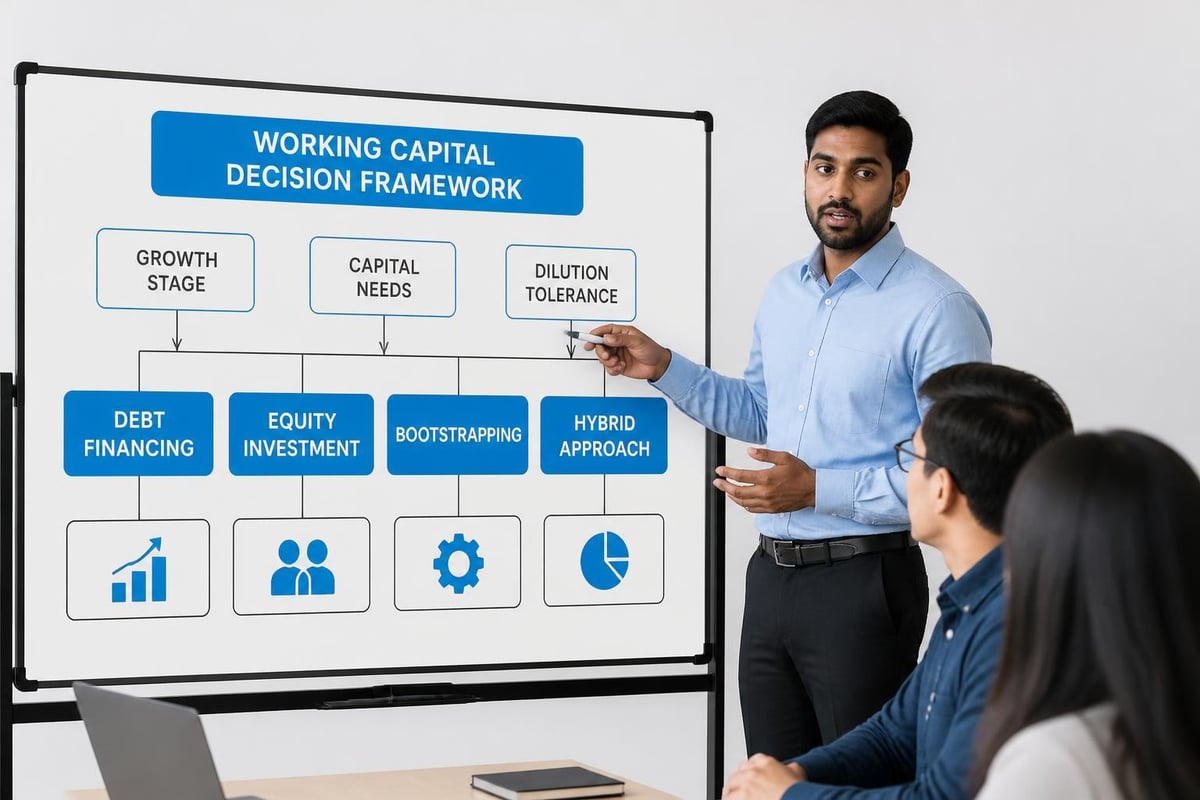
Equity investment provides capital without repayment obligations but dilutes ownership. The Federal Reserve's Financial Stability Report notes that venture capital funding has contracted in recent years, pushing more startups toward debt financing for working capital needs.
The choice depends on growth trajectory, dilution tolerance, and investor availability. Many startups combine both approaches at different stages.
Bootstrapping and Cash Flow Management
Improving cash management can reduce or eliminate the need for external working capital:
- Negotiating extended payment terms with suppliers
- Accelerating customer payments through discounts or revised terms
- Implementing just-in-time inventory systems
- Reducing operating expenses through efficiency improvements
- Converting fixed costs to variable where possible
These strategies complement rather than replace working capital financing, creating a more resilient financial foundation.
Grants and Non-Dilutive Funding
Government grants, accelerator programs, and innovation competitions offer non-dilutive capital that doesn't require repayment or equity surrender. While competitive and often restricted to specific industries or demographics, these sources can supplement working capital without adding debt service obligations.
Building Lender Relationships for Future Needs
First-time borrowers often focus exclusively on immediate needs. Strategic founders view initial working capital loans as the beginning of ongoing lender relationships.
Establishing Credit History
Successfully repaying working capital financing builds business credit and creates a track record that supports future, larger requests. Timely payments, transparent communication, and professional documentation establish credibility that pays dividends over time.
Demonstrating Growth and Reliability
Lenders track borrower performance. Startups that deploy capital effectively and achieve projected results become preferred clients eligible for better terms, higher limits, and expedited approvals. Regular financial reporting and proactive updates during the loan term strengthen these relationships.
Diversifying Funding Sources
Relying on a single lender or financing type creates vulnerability. Successful startups cultivate relationships with multiple capital sources-traditional banks, alternative lenders, credit unions, and specialized industry financiers. This diversification provides options when needs change or market conditions shift.
Common Pitfalls to Avoid
Even well-intentioned founders make mistakes when securing working capital financing.
Overborrowing and Debt Burden
The availability of capital doesn't justify taking it. Borrowing beyond genuine working capital needs or ability to repay creates unnecessary cost and risk. Conservative financial projections and honest assessment of repayment capacity prevent overextension.
Ignoring Hidden Fees and Terms
Reading the complete financing agreement prevents surprises. Common oversights include:
- Balloon payments that create sudden large obligations
- Personal guarantee provisions that put founder assets at risk
- Cross-default clauses that trigger acceleration if other debts default
- Mandatory arbitration provisions that limit legal recourse
Legal review of financing agreements provides valuable protection, especially for larger amounts or complex structures.
Mismatching Loan Terms to Business Cycles
A 6-month term loan for seasonal inventory works well if sales convert quickly. The same structure fails if the business model requires 12-month customer development. Aligning repayment schedules with revenue realization prevents cash crunches.
Working with Financing Brokers and Advisors
Navigating the complex landscape of working capital loans for startups often benefits from professional guidance. Financing brokers connect businesses with appropriate lenders and help structure applications for approval.
How Brokers Add Value
Experienced brokers understand lender appetites, documentation requirements, and approval criteria across multiple funding sources. They can:
- Match startups with lenders likely to approve their specific profile
- Prepare applications that highlight strengths and address weaknesses
- Negotiate terms and advocate for better pricing
- Streamline the process to reduce time and effort
Enterprise Finest Solutions provides working capital financing assistance by connecting startups with a network of lenders and alternative funding providers, helping identify solutions aligned with business revenue, performance, and capital requirements.
Evaluating Broker Relationships
Not all brokers deliver equal value. Quality indicators include:
- Transparency about compensation and fee structures
- Multiple lender relationships rather than single-source arrangements
- Industry experience and relevant track record
- Clear communication and realistic timeline expectations
- No upfront fees before funding placement
Reputable brokers earn compensation from lenders upon successful funding, not from application fees charged to borrowers.
DIY vs. Professional Assistance
Startups with strong financial expertise and available time may successfully navigate financing independently. Those lacking experience, facing time constraints, or pursuing larger amounts often benefit from professional assistance that improves approval odds and terms.
Working capital loans for startups provide essential liquidity to manage operations, seize opportunities, and navigate the inevitable cash-flow challenges of early-stage growth. Success requires understanding available options, qualifying criteria, strategic deployment, and cost management. Enterprise Finest Solutions connects growing businesses with flexible funding solutions through a network of lenders and alternative providers, helping identify financing that aligns with your revenue, qualifications, and capital needs to support your startup's growth trajectory.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.


