Business and Money: Smart Capital Strategies for 2026
Discover how to navigate business and money challenges in 2026. Learn capital strategies, cash flow management, and funding tactics to grow your enterprise.

The relationship between business and money has never been more complex than it is today. In 2026, companies face unprecedented financial pressures from rising interest rates, evolving lending standards, and rapid market shifts that demand both strategic foresight and tactical agility. Understanding how to effectively manage capital, optimize cash flow, and access the right funding at the right time has become essential for survival and growth in today's competitive landscape.
The Evolution of Business Finance in 2026
The landscape of business and money has transformed dramatically over the past several years. Traditional banking relationships no longer serve as the sole gateway to capital, and businesses now navigate a diverse ecosystem of funding sources that extend far beyond conventional term loans.
Financial institutions have adapted their underwriting criteria to emphasize performance metrics over static balance sheet snapshots. Revenue consistency, profit margins, customer acquisition costs, and cash conversion cycles now carry significant weight in funding decisions. This shift reflects a broader recognition that modern businesses operate differently than their predecessors, particularly in service-based and technology-enabled sectors.
Alternative Funding Sources Reshape Capital Access
The rise of alternative financing has democratized access to capital for small and medium-sized businesses. Revenue-based financing, merchant cash advances, equipment financing, and asset-based lending now complement traditional bank products.
- Revenue-based financing ties repayment to actual sales performance
- Merchant cash advances provide rapid funding based on card processing volume
- Equipment financing enables asset acquisition without depleting working capital
- Invoice factoring converts receivables into immediate cash flow
These alternatives address a critical gap in the market: businesses that generate strong revenue but lack the extensive credit history or collateral required by traditional lenders. The flexibility inherent in many alternative products allows companies to match financing costs with actual business performance rather than fixed payment schedules.
Cash Flow Management as Strategic Priority
Understanding the nuances of business and money management begins with mastering cash flow dynamics. Profitability on paper means little if a company cannot meet payroll, restock inventory, or capitalize on growth opportunities when they arise.
Cash flow forecasting has evolved from simple spreadsheet projections to sophisticated modeling that incorporates seasonality, customer payment patterns, supplier terms, and market conditions. Businesses that excel at cash flow management maintain detailed 13-week rolling forecasts that identify potential shortfalls before they become crises.
Working Capital Optimization Techniques
Effective working capital management involves balancing three critical components: accounts receivable, inventory, and accounts payable. The interplay between these elements determines how much cash remains available for operations and growth.
| Strategy | Impact | Timeline |
|---|---|---|
| Accelerate receivables collection | Improves cash position 15-30% | 30-60 days |
| Negotiate extended payment terms | Frees capital for operations | Immediate |
| Optimize inventory levels | Reduces carrying costs 10-20% | 60-90 days |
| Implement early payment discounts | Strengthens supplier relationships | Ongoing |
Businesses increasingly utilize technology platforms to automate invoicing, track payment status, and identify collection bottlenecks. These systems provide real-time visibility into cash positions and enable proactive decision-making rather than reactive crisis management.
For businesses experiencing temporary cash flow gaps or seasonal fluctuations, exploring working capital financing options can provide the flexibility needed to maintain operations while preserving long-term financial health.
Strategic Capital Allocation for Growth
The decisions companies make about allocating business and money resources directly impact their competitive positioning and growth trajectory. Capital allocation extends beyond simply deciding what to buy; it encompasses strategic choices about which opportunities to pursue, which to defer, and which to decline entirely.
High-performing businesses evaluate investment opportunities through multiple lenses: return on investment, strategic alignment, risk profile, and timing. A marketing campaign might generate lower immediate returns than equipment upgrades but could be prioritized based on long-term market positioning objectives.
Balancing Organic Growth and External Funding
The question of whether to fund growth through retained earnings or external capital represents one of the most consequential decisions business owners face. Organic growth funded by profits offers autonomy and avoids dilution or debt service obligations. However, it may limit the pace of expansion and allow competitors to capture market share.
External funding accelerates growth timelines but introduces obligations and potentially restricts operational flexibility. The optimal approach depends on:
- Market opportunity windows and competitive dynamics
- Business lifecycle stage and maturity
- Owner objectives regarding control and exit strategy
- Cost of capital versus expected returns on deployment
- Risk tolerance and financial cushion requirements
Many successful businesses employ a hybrid approach, funding baseline operations through revenue while accessing external capital for specific growth initiatives, equipment acquisitions, or market expansion efforts.
Financial Metrics That Drive Decision-Making
Data-driven management of business and money requires tracking the right metrics consistently. Financial dashboards have evolved beyond basic profit and loss statements to encompass leading and lagging indicators that provide early warning signals and strategic insights.
Essential Performance Indicators
Revenue growth rates tell only part of the story. Understanding unit economics, customer lifetime value, acquisition costs, and gross margins provides deeper insight into business health and sustainability.
Key metrics for operational financial health:
- Gross profit margin - Reveals pricing power and operational efficiency
- Operating cash flow - Indicates ability to fund operations from core business
- Days sales outstanding - Measures collection efficiency
- Current ratio - Assesses short-term liquidity position
- Debt service coverage ratio - Evaluates ability to meet financing obligations
- Return on assets - Demonstrates efficiency of capital deployment
Tracking these metrics monthly rather than quarterly enables faster course corrections and identifies trends before they become problems. Businesses that maintain strong financial discipline typically review comprehensive dashboards weekly, focusing on the handful of metrics most critical to their specific industry and business model.
Navigating Economic Uncertainty and Market Volatility
The macroeconomic environment in 2026 presents unique challenges for business and money management. Interest rate volatility affects not only the direct cost of borrowing but also customer spending patterns, supplier pricing, and overall economic confidence. Businesses must build resilience into their financial strategies rather than assuming stable conditions.
Building Financial Resilience
Resilient businesses maintain multiple financial buffers that provide flexibility during challenging periods. These include cash reserves, unused credit capacity, diversified revenue streams, and flexible cost structures.
Strategies for enhancing financial resilience:
- Diversify funding sources to avoid dependence on single lenders
- Negotiate credit facilities during strong periods, not crisis moments
- Build strong lender relationships through transparency and communication
- Maintain detailed contingency plans for revenue shortfalls
- Stress-test financial projections against pessimistic scenarios
Industry-Specific Capital Considerations
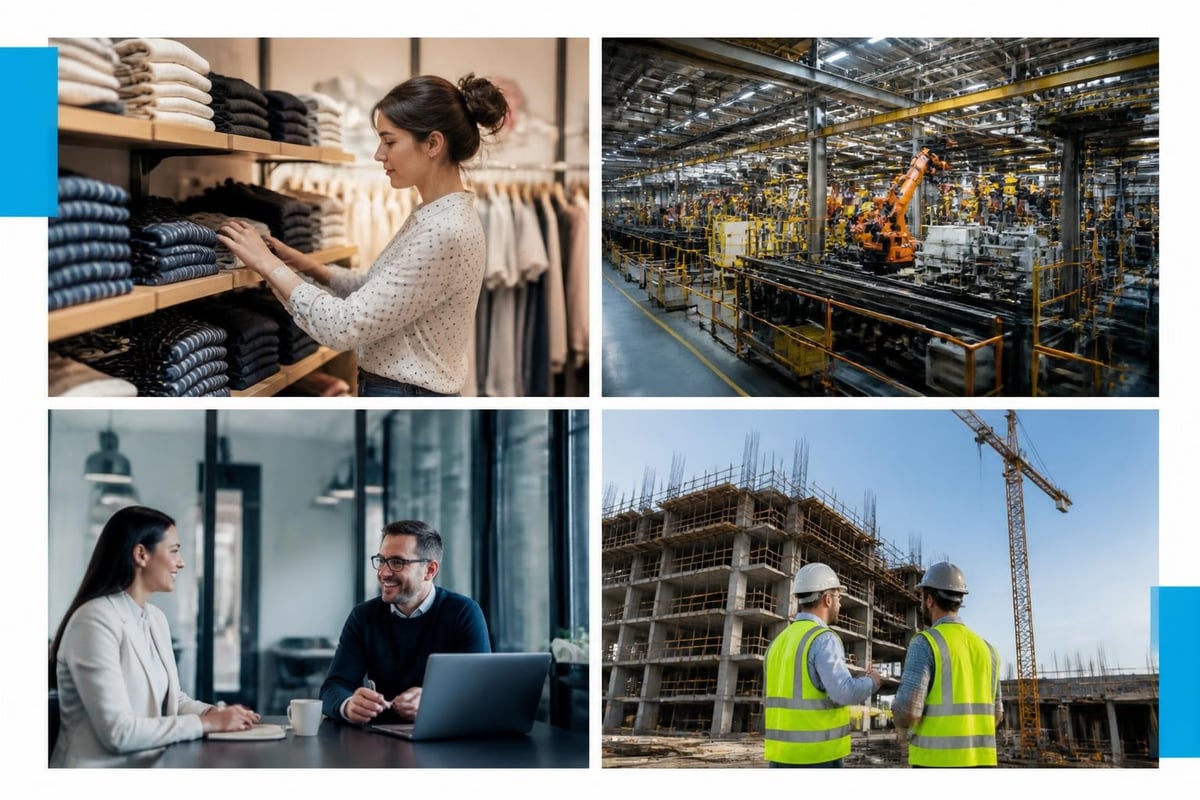
Different industries face distinct challenges in managing business and money effectively. Service businesses operate with minimal capital requirements but face cash flow volatility tied to project cycles. Manufacturing companies require significant capital investment in equipment and inventory but benefit from tangible assets that can secure financing.
| Industry | Primary Capital Need | Typical Funding Solution | Average Terms |
|---|---|---|---|
| Retail | Inventory financing | Lines of credit, inventory loans | 30-90 day cycles |
| Manufacturing | Equipment and working capital | Equipment financing, term loans | 3-7 years |
| Professional Services | Operating expenses, talent | Revenue-based, working capital | Flexible |
| Construction | Project costs, equipment | Project financing, equipment loans | Project-specific |
Technology's Role in Financial Operations
The digitization of business and money management has accelerated dramatically. Cloud-based accounting platforms, automated payment processing, AI-powered forecasting, and integrated financial dashboards have become standard tools rather than competitive advantages.
Fintech Integration and Open Banking
Open banking initiatives and API-connected financial services enable businesses to aggregate data across multiple accounts, lenders, and platforms. This consolidated view supports better cash flow forecasting and enables dynamic financial planning that adjusts to real-time conditions.
Debt Versus Equity Considerations
The fundamental choice between debt and equity financing shapes business and money dynamics for years following the decision. Debt preserves ownership but creates fixed obligations regardless of business performance. Equity brings capital without mandatory payments but dilutes ownership and may introduce governance complexity.
Evaluating Debt Capacity
Responsible debt management requires honest assessment of repayment capacity under various scenarios. A company generating $100,000 in monthly cash flow might technically support $30,000 in monthly debt service, but that leaves insufficient margin for unexpected challenges or growth investments. Prudent operators target debt service at 20-25% of stable cash flow.
Building Lender Relationships
Strong relationships with financial partners provide advantages that extend beyond competitive interest rates. Lenders who understand your business model, industry dynamics, and growth trajectory can structure financing that aligns with your actual needs rather than forcing you into standardized products.
For businesses seeking diverse funding options aligned with their specific revenue patterns and capital needs, exploring resources through platforms like Enterprise Finest Solutions can provide valuable insights into available alternatives.
Preparing for Future Capital Needs
Proactive financial planning addresses future capital requirements before they become urgent. Businesses that anticipate needs six to twelve months ahead access better terms and broader options than those seeking emergency funding under pressure.
Mastering the complexities of business and money in 2026 requires strategic thinking, disciplined execution, and access to the right financial partners and tools. Enterprise Finest Solutions connects small and medium-sized businesses with flexible funding options tailored to their revenue patterns, industry requirements, and growth objectives.
Explore Topics
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.

