Small SME Funding and Growth Guide for 2026
Essential financing, operations, and growth strategies for small SMEs. Expert guide covering capital access, compliance, and scaling challenges.
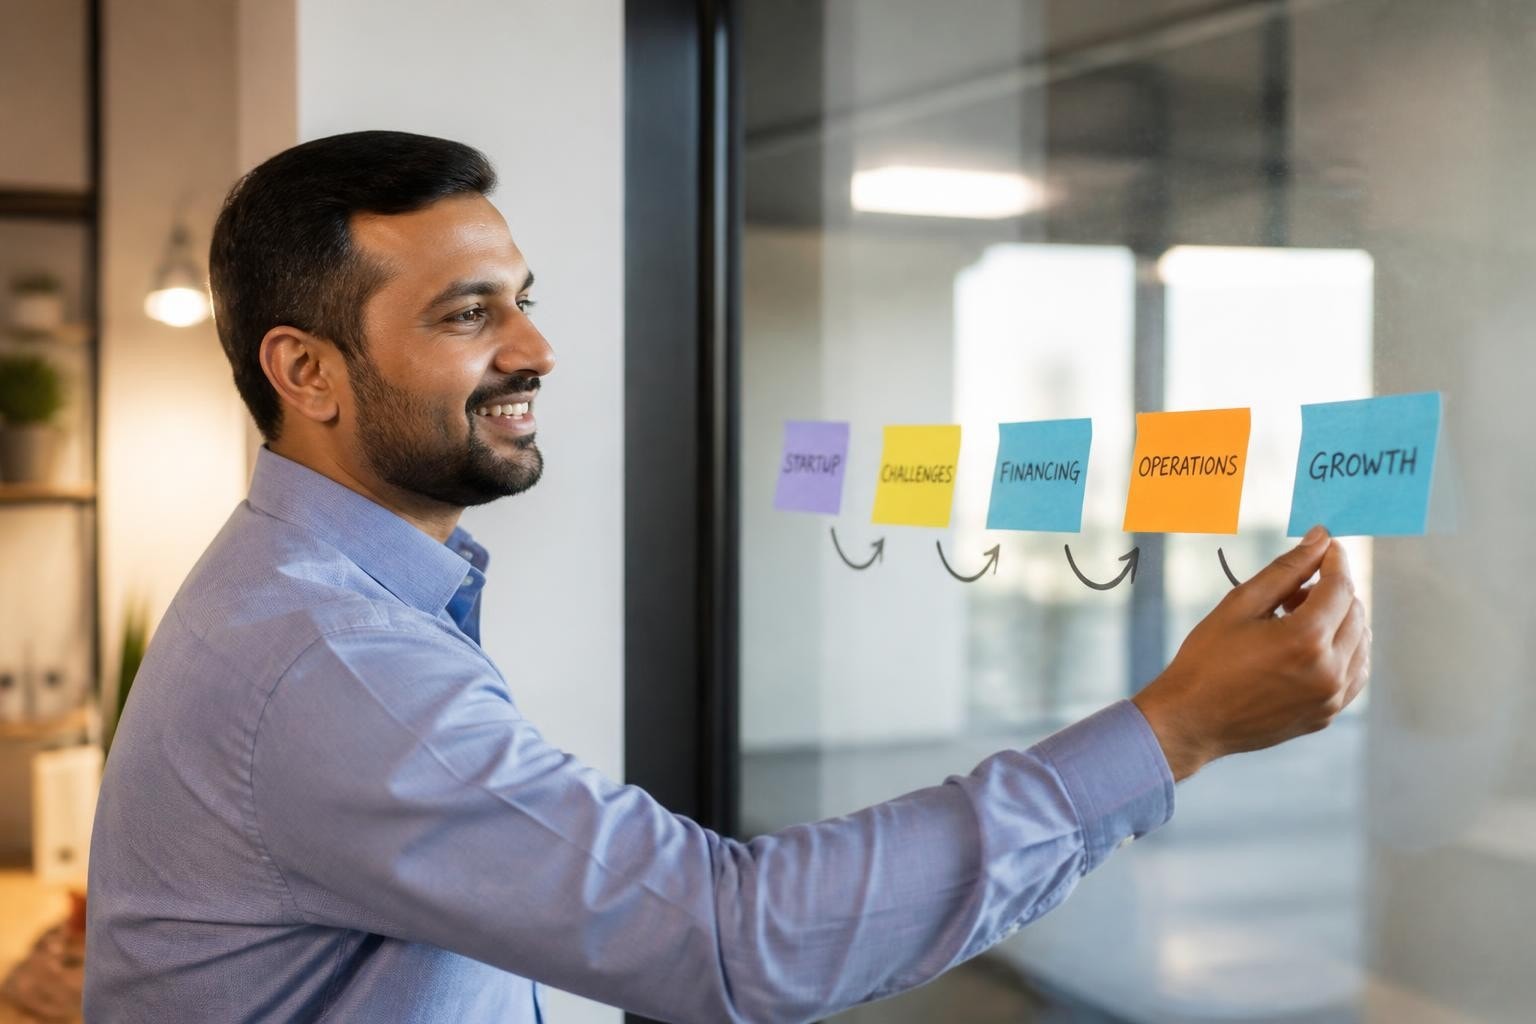
Small and medium-sized enterprises form the backbone of modern economies, yet the term "small SME" appears contradictory at first glance. Since SME already encompasses both small and medium businesses, why the redundancy? In practice, business owners, lenders, and policy makers often use "small sme" to distinguish truly small enterprises from their medium-sized counterparts, highlighting businesses that face unique challenges in accessing capital, implementing technology, managing compliance, and competing for talent. These organizations typically employ fewer than 50 people, generate under $10 million in annual revenue, and operate with constrained resources that demand creative problem-solving and strategic capital deployment.
Understanding the Small SME Landscape
The small sme category represents businesses that have moved beyond startup phase but haven't yet achieved the operational scale or financial stability of larger enterprises. These companies occupy a critical economic position, driving local employment, fostering innovation in niche markets, and contributing significantly to tax revenues across North America.
Defining Characteristics and Operational Realities
Small sme operations differ fundamentally from both startups and established mid-market firms. Most function with lean teams where employees wear multiple hats, limited cash reserves that make timing crucial, and dependence on founder expertise rather than institutional knowledge. The World Bank's SME finance research consistently identifies a financing gap affecting these businesses, with traditional lenders viewing them as too risky while alternative financing options may seem too expensive.
Revenue patterns in small sme environments often display seasonal volatility or cyclical swings tied to specific industries. A restaurant might see dramatic differences between summer and winter months, while a B2B services firm could experience quarterly fluctuations based on client budget cycles. This variability complicates traditional underwriting models that banks rely upon.
Market Position and Competitive Dynamics
Small SME operators compete simultaneously against larger firms with economies of scale and smaller startups with lower overhead. Success requires identifying defensible niches where personalized service, specialized expertise, or local presence create sustainable advantages.
| Competitive Factor | Small SME Challenge | Strategic Response |
|---|---|---|
| Pricing power | Limited volume discounts | Emphasize quality and specialization |
| Technology adoption | Constrained IT budgets | Focus on high-ROI tools first |
| Talent acquisition | Can't match corporate salaries | Offer flexibility and growth opportunities |
| Marketing reach | Smaller advertising budgets | Leverage digital channels and partnerships |
Capital Access and Financing Solutions
Perhaps no challenge defines the small sme experience more acutely than securing appropriate financing. Traditional bank loans often remain out of reach due to limited collateral, short operating histories, or credit profiles that don't fit conventional boxes. Yet capital needs persist: inventory must be purchased, payroll met, equipment upgraded, and opportunities seized when market conditions align.
Alternative Financing Pathways
The financing landscape has evolved considerably over the past decade, creating options specifically designed for small sme cash flow patterns and qualification profiles. Revenue-based financing considers actual business performance rather than solely focusing on credit scores and collateral. Merchant cash advances provide rapid access to capital based on sales volume, particularly useful for retail and hospitality operations.
For businesses experiencing seasonal fluctuations or managing irregular expenses, exploring a business line of credit through qualified brokers can provide the flexibility to draw funds only when needed, potentially reducing overall financing costs compared to lump-sum loans.
Equipment financing allows small sme operators to acquire necessary machinery, vehicles, or technology while preserving working capital for daily operations. The equipment itself typically serves as collateral, simplifying approval processes for businesses without substantial real estate or other pledgeable assets.
Evaluating Financing Options
Small SME decision-makers should approach financing with clear understanding of total costs, repayment structures, and operational impact. A financing solution that appears affordable on monthly payment schedules might prove expensive when examined through annual percentage rate calculations. Conversely, options with higher stated costs might deliver better overall value if they prevent stockouts, enable timely expansion, or avoid missed opportunities.
- Cost of capital: Compare all fees, interest rates, and repayment terms across options
- Speed to funding: Consider how quickly capital becomes available relative to business needs
- Repayment flexibility: Assess whether payment structures align with revenue patterns
- Qualification requirements: Understand minimum revenue thresholds, time in business, and credit expectations
- Use restrictions: Verify that financing can be applied to intended business purposes
Operational Excellence for Small Enterprises
Small sme success depends heavily on operational efficiency since resource constraints leave little room for waste or redundancy. Every dollar, hour, and team member must contribute meaningfully to business objectives. This reality demands systems thinking even in organizations too small to employ dedicated operations managers.
Process Standardization and Documentation
Growing small SME operators frequently discover that undocumented tribal knowledge creates bottlenecks when key employees are unavailable or when training new team members. Investing time in standard operating procedures, even simple checklists and workflow diagrams, pays dividends through reduced errors, faster training, and improved consistency.
Process documentation need not be elaborate. A one-page checklist for opening procedures, a simple flowchart for order fulfillment, or a shared spreadsheet tracking routine maintenance schedules can substantially improve operational reliability. The goal is capturing essential knowledge before it's urgently needed.
Technology Leverage Without Overinvestment
Small sme technology strategies should prioritize high-impact, low-complexity solutions over comprehensive enterprise systems. Cloud-based accounting platforms, customer relationship management tools, and project management software deliver immediate value without requiring extensive IT infrastructure or dedicated support staff.
Cybersecurity deserves particular attention as small businesses increasingly face targeted attacks from sophisticated threat actors who perceive them as easier targets than large corporations. The NIST Cybersecurity Framework 2.0 Small Business Quick-Start Guide provides practical, implementable controls that protect critical assets without requiring enterprise-level security budgets.
Regulatory Compliance and Tax Management
Small SME operators often struggle with the compliance burden that affects businesses of all sizes but hits hardest when no dedicated legal or accounting department exists. Requirements span federal, state or provincial, and local jurisdictions, covering employment law, tax obligations, industry-specific regulations, and licensing requirements.
Tax Planning and Obligations
Effective tax management for a small sme extends beyond annual filing to encompass quarterly estimated payments, employment tax withholding, sales tax collection and remittance, and strategic timing of major purchases or expense recognition. The IRS Tax Guide for Small Business offers comprehensive guidance on federal obligations, though businesses should consult qualified tax professionals for complex situations or multi-state operations.
Common tax pitfalls include:
- Misclassifying workers as independent contractors when employment law requires employee status
- Failing to track deductible expenses throughout the year, resulting in overpayment
- Missing estimated payment deadlines, triggering penalties and interest charges
- Inadequate documentation of business use for vehicles, home offices, or equipment
- Overlooking available credits for research activities, hiring, or energy efficiency improvements
Employment Law and Workplace Compliance
Small sme employers must navigate the same employment regulations as major corporations, from wage and hour requirements to anti-discrimination protections, workplace safety standards, and family leave provisions. Requirements often vary based on employee count, with certain obligations triggering at 15, 20, or 50 employees, but many protections apply regardless of company size.
Maintaining compliance requires staying current with minimum wage changes, updating employee handbooks when regulations evolve, posting required notices in accessible locations, and maintaining proper records of hours worked, wages paid, and personnel actions. The Small Business Administration provides extensive guidance on federal requirements, though state and local laws frequently impose additional obligations.
Growth Strategies and Scaling Considerations
Scaling a small sme presents unique challenges distinct from both startup growth and enterprise expansion. The business possesses established operations and customer relationships but lacks the capital reserves, management depth, and operational systems that facilitate rapid expansion. Growth must be calibrated carefully to avoid overextending resources while capturing market opportunities.
Strategic Growth Pathways
| Growth Strategy | Capital Requirements | Risk Profile | Timeline to Results |
|---|---|---|---|
| Geographic expansion | Moderate to High | Medium-High | 12-24 months |
| Product/service line extension | Low to Moderate | Medium | 6-12 months |
| Strategic partnerships | Low | Low-Medium | 3-9 months |
| Franchise/licensing model | Low (franchisor) | Medium | 18-36 months |
| Digital transformation | Moderate | Medium | 6-18 months |
Small SME growth often succeeds best through focused execution rather than simultaneous pursuit of multiple opportunities. Expanding into a second location while launching new product lines and implementing major technology changes typically overwhelms available management capacity and capital resources. Sequential prioritization allows learning from each initiative before committing to the next.
Building Management Capacity
Many small sme owners discover that their own capacity becomes the primary constraint on growth. Moving from working in the business to working on the business requires delegating operational responsibilities, developing leadership within the team, and creating systems that function reliably without constant founder intervention.
This transition rarely happens smoothly. Founders who built businesses through personal expertise, customer relationships, and hands-on problem-solving must learn to lead through others, often experiencing discomfort as they relinquish direct control over familiar tasks. Investing in management development, whether through formal training, peer groups, or coaching relationships, accelerates this critical transition.
Market Access and Customer Acquisition
Small sme marketing budgets can't compete with enterprise-level advertising spending, requiring creative approaches to customer acquisition and retention. Success depends on identifying channels where targeted messaging reaches high-probability prospects without competing against unlimited budgets from larger competitors.
Digital Marketing Efficiency
Digital channels offer small sme operators opportunities to reach specific audiences with measurable results and adjustable budgets. Search engine marketing, when focused on long-tail keywords reflecting specific customer intent, can generate qualified leads without bidding against major competitors on expensive generic terms. Social media marketing builds community and brand awareness, particularly effective for visual products, local services, or businesses targeting specific demographic segments.
Content marketing-creating valuable information that attracts and engages target audiences-plays to small sme strengths by showcasing specialized expertise and building trust over time. A consulting firm might publish case studies demonstrating problem-solving approaches, while a specialty manufacturer could create technical guides helping customers select appropriate products.
Customer Retention Economics
For most small SME operations, retaining existing customers proves far more cost-effective than acquiring new ones. Repeat business generates higher profit margins since no acquisition costs are incurred, customers familiar with products require less support, and satisfied clients often provide referrals that expand customer base organically.
Systematic retention efforts include:
- Regular communication through newsletters, updates, or personalized outreach
- Loyalty programs rewarding repeat purchases or referrals
- Proactive service check-ins identifying issues before they prompt defection
- Customer feedback mechanisms that demonstrate responsiveness to concerns
- Exclusive offers or early access for existing clients
International Expansion Opportunities
While many small sme operators focus exclusively on domestic markets, international expansion increasingly offers accessible growth opportunities. E-commerce platforms enable selling across borders with minimal infrastructure investment, while trade agreements and logistics networks simplify shipping and customs processes. The World Trade Organization's analysis of SME participation in international trade highlights both the opportunities and barriers small firms face when exploring global markets.
Cross-border expansion requires careful consideration of product adaptation, pricing strategies that reflect local purchasing power and competition, payment processing that accommodates international transactions, and customer service capabilities spanning time zones and languages. Starting with markets sharing language and cultural similarities often provides the smoothest entry path before tackling more complex international environments.
Currency risk, intellectual property protection, and regulatory compliance in foreign jurisdictions introduce complexity that demands expert guidance. Small sme operators should leverage trade promotion agencies, export assistance programs, and experienced advisors rather than navigating unfamiliar terrain independently.
Succession Planning and Exit Strategies
Even small sme owners focused on current operations benefit from considering eventual transition plans. Whether through family succession, management buyout, strategic sale, or other exit paths, advance planning maximizes options and business value when the time comes to transition.
Business valuation for small SME entities typically relies on multiple of earnings approaches, though asset-heavy businesses might use book value methods and unique situations may justify custom methodologies. Professional valuations provide realistic expectations and identify value drivers that ownership can enhance before exit.
Preparing a business for transition involves documenting systems, reducing customer concentration, developing management independence from founders, and ensuring clean financial records. These improvements don't just facilitate eventual sale-they strengthen current operations and increase enterprise value regardless of ownership timeline.
Small SME success in 2026 requires balancing immediate operational demands with strategic positioning for sustainable growth, all while managing constrained resources and competing against larger, better-capitalized competitors. From securing appropriate financing and implementing efficient operations to navigating compliance requirements and developing scalable systems, small business owners face multifaceted challenges demanding both tactical execution and strategic vision. When capital needs arise to fund inventory, bridge cash flow gaps, or seize growth opportunities, Enterprise Finest Solutions helps small and medium-sized businesses explore flexible financing options aligned with their revenue, performance, and specific business requirements.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.