Small Business Loans for Veterans: Your 2026 Guide
Discover small business loans for veterans in 2026. Learn about SBA programs, lender advantages, eligibility, and funding strategies for service members.
Veterans returning to civilian life often channel their leadership, discipline, and problem-solving skills into entrepreneurship. The transition from military service to business ownership requires not just vision and determination, but also adequate capital to launch and grow a venture. Small business loans for veterans have become increasingly accessible in 2026, with government programs, private lenders, and alternative financing providers offering specialized options designed specifically for those who served. Understanding the landscape of available funding, eligibility requirements, and strategic advantages can make the difference between a struggling startup and a thriving enterprise.
Why Veterans Make Strong Business Owners
Military service cultivates unique qualities that translate directly into business success. Veterans bring operational discipline, strategic thinking, and crisis management experience to their entrepreneurial ventures. These attributes make former service members attractive borrowers to lenders evaluating small business loans for veterans.
Research consistently shows veteran-owned businesses demonstrate higher survival rates than their non-veteran counterparts. The structured training, teamwork orientation, and mission-focused mindset developed during military service create a foundation for systematic business planning and execution. Lenders recognize these patterns and increasingly tailor products to support veteran entrepreneurs.
Skills That Attract Lenders
- Leadership under pressure translates to confident decision-making during business challenges
- Resource optimization from military logistics applies to cash flow management and operational efficiency
- Team building and delegation create scalable organizational structures
- Clear communication protocols improve vendor relationships and customer service
- Adaptability to changing conditions helps businesses pivot when market dynamics shift
Financial institutions value these competencies when underwriting small business loans for veterans. The combination of practical experience and proven reliability reduces perceived lending risk.
SBA Loan Programs Designed for Veterans
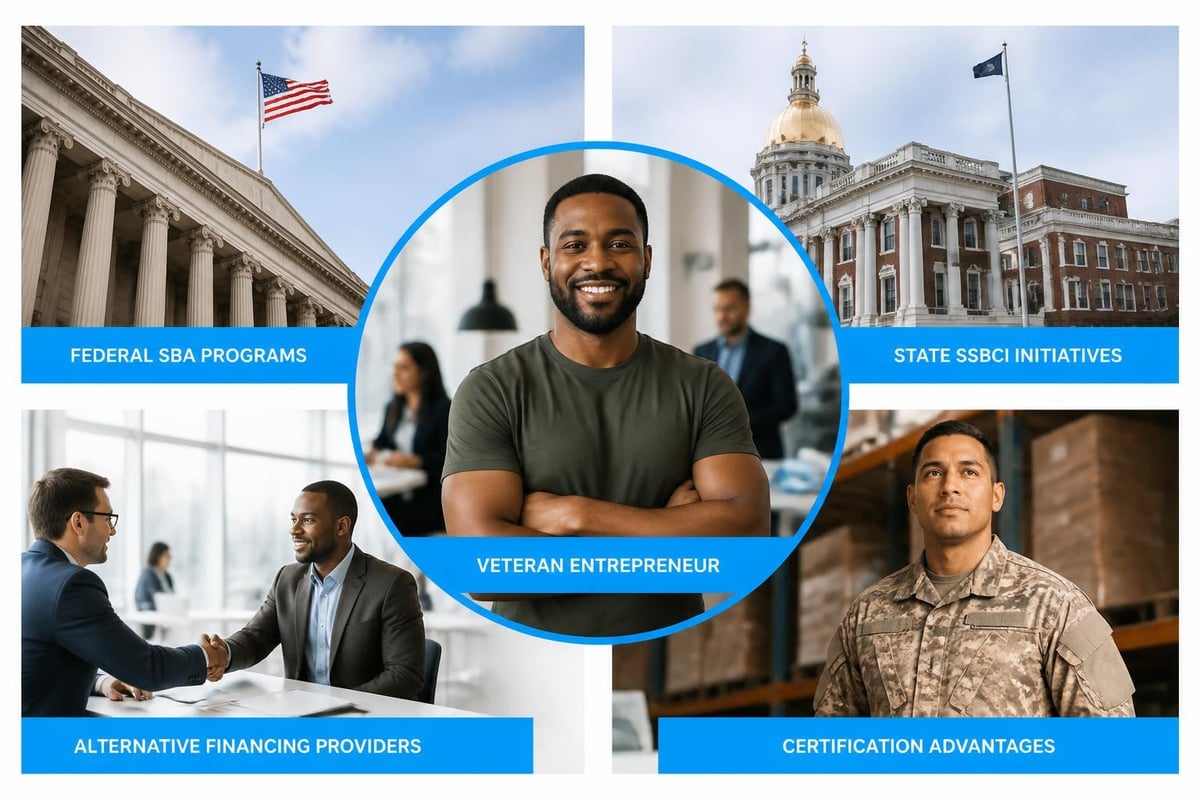
The Small Business Administration offers the most comprehensive support structure for veteran entrepreneurs seeking capital. The SBA's veteran-specific resources include several distinct advantages within standard loan programs, making them the cornerstone of small business loans for veterans in 2026.
SBA 7(a) Loan Program Benefits
The flagship 7(a) loan program provides working capital, equipment financing, real estate purchases, and refinancing up to $5 million. Veterans receive tangible benefits:
| Veteran Advantage | Standard Borrower | Veteran Borrower |
|---|---|---|
| SBA guarantee fee (loans ≤$500K) | Up to 3.75% | Waived completely |
| SBA guarantee fee (loans $500K–$1M) | Up to 3.75% | Waived completely |
| SBA guarantee fee (loans >$1M) | Up to 3.75% | Waived completely |
| Annual savings on $350K loan | $0 | Approximately $13,125 |
This fee waiver represents substantial upfront savings that improve cash flow during critical startup phases. Veterans using the 7(a) program can redirect these savings toward inventory, marketing, or operational reserves.
SBA 504 Loan Program for Veterans
The 504 program finances fixed assets including commercial real estate, buildings, and major equipment. The structure typically involves:
- 10% down payment from the business owner (veterans may qualify for reduced equity requirements)
- 50% from a conventional lender covering half the project cost
- 40% from a Certified Development Company (CDC) backed by SBA guarantee
Veterans benefit from the same guarantee fee waivers on the CDC portion, reducing transaction costs significantly. This program works particularly well for manufacturing facilities, restaurants, medical offices, and retail locations requiring substantial physical infrastructure.
SBA Express and Community Advantage Loans
These streamlined options offer faster approval for smaller capital needs up to $500,000. The Veterans Business Outreach Center program provides local counseling to help veterans navigate these faster-track products. Express loans feature 36-hour SBA review periods, making them ideal for time-sensitive opportunities.
Alternative Small Business Loans for Veterans
Traditional bank loans represent just one avenue for veteran entrepreneurs. Alternative financing has expanded dramatically, offering speed and flexibility that complement SBA programs.
Revenue-Based Financing Options
Many veterans operate service businesses, retail locations, or restaurants with consistent monthly revenue but limited collateral. Revenue-based financing and merchant cash advances evaluate funding eligibility based primarily on business performance rather than extensive documentation or perfect credit history.
Business owners exploring working capital financing can often qualify based on their monthly revenue patterns. These products advance capital in exchange for a percentage of future sales, with daily or weekly remittances that align with cash flow. Approval timelines often run days rather than weeks, supporting veterans who need to act quickly on growth opportunities.
Key advantages for veteran-owned businesses:
- Minimal documentation compared to traditional bank loans
- Approval based on business performance metrics
- Fast funding (often 2-5 business days)
- No fixed monthly payments during slow periods
- Flexible use of capital for any business purpose
The trade-off involves higher cost of capital compared to SBA products, but the speed and accessibility make these alternatives valuable for established businesses facing immediate needs.
Equipment Financing for Veteran Entrepreneurs
Veterans entering industries like construction, transportation, manufacturing, or healthcare often need specialized equipment. Equipment-specific financing uses the purchased asset as collateral, improving approval odds for newer businesses without extensive operating history.
This approach allows veterans to preserve working capital while acquiring necessary tools, vehicles, or machinery. Terms typically range from 24 to 84 months depending on equipment useful life, with competitive rates reflecting the secured nature of the transaction.
Eligibility Requirements and Documentation
Understanding what lenders require streamlines the application process for small business loans for veterans. Requirements vary by product type, but common elements include:
Standard Documentation Package
- Business plan outlining market opportunity, competitive positioning, and financial projections
- Personal financial statements for all owners with 20% or more equity
- Business financial statements (income statement, balance sheet, cash flow statement)
- Tax returns (personal and business, typically two years)
- DD-214 form or other military service documentation
- Legal documents (licenses, registrations, articles of incorporation)
- Collateral information and ownership documentation when applicable
The Federal Reserve's research on credit availability shows that preparation significantly impacts approval rates. Veterans who organize documentation systematically and present clear use-of-funds explanations experience smoother underwriting.
Credit Score Considerations
Most lenders examine both personal and business credit when evaluating small business loans for veterans. Typical thresholds include:
| Loan Type | Minimum Credit Score | Preferred Score |
|---|---|---|
| SBA 7(a) | 640-650 | 680+ |
| SBA Express | 660-680 | 700+ |
| Traditional bank | 680-700 | 720+ |
| Alternative financing | 550-600 | 620+ |
Veterans with service-connected challenges affecting credit history should explore lender programs offering manual underwriting review. Many institutions consider context and trajectory rather than applying purely algorithmic decisions.
Special Advantages and Certifications
Beyond loan program benefits, veterans can leverage certifications that open additional opportunities and improve competitive positioning.
Service-Disabled Veteran-Owned Small Business (SDVOSB)
The VA Office of Small & Disadvantaged Business Utilization administers certification for service-disabled veterans. This designation provides:
- Access to set-aside federal contracts reserved exclusively for SDVOSBs
- Competitive advantages in federal procurement worth billions annually
- Enhanced credibility with commercial clients valuing veteran partnerships
- Potential eligibility for state and local procurement preferences
Federal agencies must award 3% of contracting dollars to SDVOSBs, creating substantial market opportunities. Veterans carrying service-connected disabilities should pursue this certification alongside financing applications to maximize business development potential.
Veteran-Owned Small Business (VOSB) Certification
Similar to SDVOSB but without the disability requirement, VOSB certification opens doors to:
- Federal contracts set aside for veteran-owned firms
- Corporate supplier diversity programs
- State-level preferences and incentives
- Networking through veteran business associations
These certifications complement small business loans for veterans by improving revenue predictability through government contracts. Lenders view certified businesses with federal contracts as lower-risk borrowers due to reliable payment streams.
State and Local Veteran Financing Programs
The federal landscape represents just one layer of available support. State programs often provide guarantees, direct loans, or grants specifically targeting veteran entrepreneurs.
State Small Business Credit Initiative (SSBCI)
The U.S. Treasury's SSBCI program allocates billions to states for small business support. Many states designate portions specifically for veteran-owned businesses through:
- Loan guarantee programs reducing lender risk on conventional loans
- Loan participation programs where states fund a portion alongside private lenders
- Collateral support programs providing additional security for undercollateralized loans
- Capital access programs creating reserve funds for portfolio losses
Veterans should investigate their state's SSBCI deployment strategy. Programs vary significantly by jurisdiction, with some offering veteran-specific set-asides or enhanced terms.
Examples of State-Level Programs
Texas: The Veterans Entrepreneur Program provides low-interest loans up to $25,000 for business startup costs and working capital, with favorable terms recognizing military service.
California: California Capital Access Program (CalCAP) for small businesses includes veteran-friendly enrollment fees and enhanced coverage percentages for qualifying veteran entrepreneurs.
New York: The New York State Division of Veterans' Services connects veterans with multiple funding streams and provides navigation assistance through state-specific programs.
Research indicates that strategic use of state programs expands capital access particularly in underserved markets. Veterans in rural areas or economically distressed regions may find state programs fill gaps where traditional lenders hesitate.
Preparing a Winning Loan Application
Success with small business loans for veterans depends heavily on application quality. Strong submissions share common characteristics that demonstrate preparedness and strategic thinking.
Business Plan Essentials
Your business plan serves as the primary tool for communicating vision and viability. Include:
- Executive summary capturing the opportunity concisely
- Market analysis demonstrating demand and competitive gaps
- Organization and management highlighting your military experience and relevant civilian expertise
- Service or product line detailing what you sell and unique value proposition
- Marketing and sales strategy explaining customer acquisition approaches
- Financial projections with realistic revenue, expense, and cash flow forecasts
- Funding request specifying exact amount needed and precise use of funds
Lenders evaluating small business loans for veterans particularly value clear connections between military experience and business operations. A logistics specialist starting a supply chain consulting firm or a medic launching a home healthcare agency presents natural credibility that should be explicitly highlighted.
Financial Projection Best Practices
- Build conservative revenue assumptions rather than optimistic scenarios
- Include detailed expense breakdowns showing understanding of operational costs
- Demonstrate break-even analysis and time to profitability
- Show multiple scenarios (conservative, moderate, optimistic) to prove planning depth
- Align funding request with specific timeline and milestones
Financial institutions trust veterans who apply military planning discipline to business forecasting. Present numbers that reflect careful research and realistic market assessment.
Common Pitfalls to Avoid
Even strong veteran entrepreneurs encounter obstacles when seeking business financing. Awareness of frequent mistakes improves approval probability.
Undercapitalization Requests
Many first-time business owners request insufficient capital to properly launch and sustain operations through the startup phase. The business plan must account for:
- Working capital needs during ramp-up before positive cash flow
- Unexpected expenses and contingency reserves (typically 10-20% buffer)
- Marketing and customer acquisition costs often underestimated by new businesses
- Inventory requirements for product-based businesses
- Payroll obligations before revenue reaches sustainable levels
Requesting too little capital creates stress and potential failure when reserves deplete. Lenders prefer seeing thoughtful capitalization that demonstrates business acumen.
Incomplete Documentation
Missing documents delay underwriting and signal lack of preparation. Veterans should compile complete packages before application submission. Common omissions include:
- Current business licenses and permits
- Lease agreements or property documentation
- Vendor contracts or customer agreements demonstrating viability
- Insurance policies (general liability, professional liability, property)
- Partnership agreements or operating agreements for multi-owner businesses
Organization reflects military discipline. Present documentation systematically to reinforce your operational competence.
Ignoring Credit Issues
Addressing credit challenges proactively demonstrates integrity. If your credit history includes late payments, collections, or other negatives, prepare explanations that provide context. Many issues result from:
- Deployment-related payment management difficulties
- Medical expenses from service-connected conditions
- Transition period unemployment or underemployment
- Identity theft or administrative errors
Lenders respond positively to honest disclosure paired with evidence of resolution and improved patterns. Hiding issues until they surface during underwriting damages credibility.
Maximizing Approval Probability
Strategic approaches improve outcomes when pursuing small business loans for veterans. These tactics leverage your veteran status while demonstrating business sophistication.
Building Lender Relationships
Start conversations with lenders well before you need capital. Many veterans benefit from:
- Establishing business banking relationships early with institutions offering veteran programs
- Attending veteran entrepreneur networking events where lenders actively participate
- Seeking introductions through veteran business organizations and chambers of commerce
- Consulting with VBOCs that maintain lender partnerships and can facilitate connections
Relationship lending still influences decisions, particularly at community banks and credit unions serving veteran populations. Face-to-face interactions allow you to communicate capabilities that transcend paper applications.
Leveraging Professional Advisors
Military culture emphasizes knowing when to seek expert support. Business financing involves complexity that rewards specialist guidance:
- Accountants ensure financial statements meet lender standards and tax strategies optimize business structure
- Attorneys review contracts, entity formation, and regulatory compliance
- Business consultants refine plans and identify operational improvements
- Financing brokers navigate multiple lender options and match businesses to appropriate products
Working with professionals demonstrates serious commitment and often surfaces better financing alternatives than independent research reveals.
Timing Your Application
Market conditions and personal circumstances both affect approval outcomes. Consider:
- Seasonal revenue patterns in your industry that might influence projections
- Personal financial stability timing applications when your personal finances show strength
- Business milestones such as securing a major contract or reaching revenue thresholds
- Credit improvement activities allowing time for positive changes to reflect in scores
- Economic indicators as lending standards tighten or loosen with broader conditions
Veterans should approach financing strategically rather than reactively. Planning application timing around optimal conditions improves terms and approval likelihood.
Beyond Traditional Bank Financing
The 2026 financing landscape offers veterans multiple paths to capital beyond conventional bank loans. Diversification creates resilience and matches different needs with appropriate solutions.
Grants and Non-Dilutive Capital
While less common than loans, veteran-focused grants provide capital without repayment obligations or equity sacrifice:
- FedEx Small Business Grant Contest includes veteran-specific categories
- Veteran-focused nonprofit organizations offering startup grants ranging from $1,000 to $50,000
- State economic development agencies with veteran entrepreneur grant programs
- Industry associations providing specialty grants for specific sectors
Competition typically requires strong applications, but the zero-cost capital justifies the effort. Combine grant funding with small business loans for veterans to minimize debt burden.
Home Equity and Personal Assets
Many veteran homeowners leverage property equity to fund business ventures. VA loan benefits often result in substantial home equity that can be accessed through:
- Home equity lines of credit (HELOCs) offering lower interest rates than unsecured business financing
- Cash-out refinancing converting equity to lump-sum capital
- Second mortgages structured as fixed-term loans secured by property
Personal asset utilization requires careful risk assessment. Mixing personal and business finances increases personal exposure if the venture struggles, but lower capital costs can accelerate growth and profitability.
Crowdfunding and Community Support
Veteran-owned businesses often generate strong community support translating into crowdfunding success:
- Rewards-based platforms (Kickstarter, Indiegogo) pre-sell products or services
- Equity crowdfunding (StartEngine, Wefunder) allows public investment in exchange for ownership stakes
- Donation-based platforms supporting mission-driven veteran ventures
- Community development financial institutions (CDFIs) focused on veteran and military family lending
These alternatives supplement rather than replace small business loans for veterans, but provide valuable proof of concept and early revenue.
Long-Term Capital Strategy
Successful veteran entrepreneurs think beyond initial capitalization toward sustainable growth financing. Strategic planning encompasses multiple funding stages aligned with business maturity.
Growth Stage Financing
As businesses establish track records, funding options expand significantly:
| Business Stage | Typical Financing Options | Qualification Drivers |
|---|---|---|
| Startup (Year 0-1) | SBA Microloans, grants, personal assets | Personal credit, plan quality |
| Early Growth (Year 1-3) | SBA 7(a), revenue-based financing, equipment loans | Revenue history, profitability trend |
| Expansion (Year 3-5) | SBA 504, conventional term loans, lines of credit | Established financials, equity position |
| Maturity (Year 5+) | Asset-based lending, private equity, acquisition financing | Multiple years profitability, market position |
Planning capital needs across growth stages prevents scrambling for emergency funding during transitions. Veterans should revisit financing strategy annually as business circumstances evolve.
Building Business Credit
Separating business and personal credit strengthens long-term financing capacity:
- Establish business entity (LLC, Corporation, Partnership)
- Obtain federal EIN from the IRS
- Register with business credit bureaus (Dun & Bradstreet, Experian Business, Equifax Business)
- Open business bank accounts and credit cards in company name
- Establish trade credit with vendors reporting to business bureaus
- Maintain perfect payment history on all business obligations
Strong business credit eventually reduces dependence on personal guarantees and improves borrowing terms. Veterans should prioritize credit building from day one of operations.
Small business loans for veterans provide critical capital access through specialized programs recognizing military service value and business potential. Veterans navigating financing options benefit from combining federal SBA advantages, state programs, and alternative financing to match their specific capital needs, timeline requirements, and business circumstances. Whether you're launching your first venture or expanding an established operation, Enterprise Finest Solutions connects veteran business owners with funding partners and flexible financing options aligned with your revenue, performance, and growth objectives.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.