OnDeck Funding: A Comprehensive Guide for Business Owners
Explore OnDeck funding options for small businesses. Learn about eligibility, application process, loan products, and alternatives in 2026.
Small businesses seeking rapid access to capital frequently encounter OnDeck as a prominent alternative lending option. OnDeck funding has become synonymous with fast, technology-driven business financing that prioritizes revenue performance and business fundamentals over traditional credit metrics alone. Understanding how ondeck funding works, what it offers, and how it compares to other financing solutions can help business owners make informed decisions about their capital needs in 2026.
Understanding OnDeck Funding and Its Market Position
OnDeck has established itself as a pioneer in the online small business lending space since its founding in 2007. The company leveraged technology and data analytics to streamline the underwriting process, making ondeck funding accessible to businesses that might struggle with traditional bank requirements. In 2020, Enova International acquired OnDeck, creating a diversified fintech lending platform that serves both consumer and small business markets.
The Evolution of Alternative Business Lending
The small business lending landscape has transformed dramatically over the past decade. Traditional banks once dominated commercial lending, but regulatory constraints and risk aversion created opportunities for fintech lenders to fill the gap. OnDeck funding emerged during this shift, offering:
- Automated underwriting that evaluates business performance holistically
- Speed of funding with decisions in hours rather than weeks
- Flexibility for businesses with shorter operating histories
- Technology integration through APIs and digital platforms
- Transparent pricing with clear disclosure of costs and terms
This approach resonated with small businesses that needed capital quickly and didn't fit traditional lending boxes. The 2024 FDIC Small Business Lending Survey confirms that non-bank lenders now account for a significant and growing share of small business credit origination, particularly for loans under $250,000.
OnDeck Funding Products and Loan Structures
Understanding the specific products available through ondeck funding helps businesses identify whether these solutions align with their financing needs. OnDeck primarily offers two core products, each designed for different business scenarios and capital requirements.
Term Loans
OnDeck's term loan product provides a lump sum of capital repaid over a fixed period. These loans typically feature:
| Feature | Details |
|---|---|
| Loan amounts | $5,000 to $250,000 (varies by qualification) |
| Repayment terms | 3 to 36 months |
| Payment frequency | Daily or weekly automatic withdrawals |
| Funding speed | Same-day to next-day funding possible |
| Prepayment | Allowed, with varying savings on interest |
The term loan structure works well for businesses with specific, one-time capital needs such as equipment purchases, inventory buildup, or facility improvements. The fixed repayment schedule provides predictability, though the daily or weekly payment structure differs from traditional monthly loan payments.
Lines of Credit
For businesses needing flexible, ongoing access to capital, OnDeck offers revolving credit lines. These function similarly to business credit cards but typically offer higher limits and lower costs than merchant cash advances.
Key characteristics include:
- Credit limits ranging from $6,000 to $100,000
- Draw period allowing repeated borrowing up to the limit
- Interest charges only on outstanding balances
- Renewal potential for qualified borrowers
- Quick access to additional capital as needs arise
The line of credit product suits businesses with fluctuating cash flow, seasonal operations, or recurring working capital gaps. Business owners can access funds as needed and only pay for what they use, making this a cost-effective option when capital needs are unpredictable.
For comparison, businesses exploring broader working capital solutions may also consider options like working capital financing, which encompasses various structures tailored to different revenue patterns and business models.
Eligibility Requirements and Qualification Criteria
OnDeck funding uses technology-driven underwriting that evaluates multiple data points to assess creditworthiness. While specific requirements evolve, the general qualification framework for ondeck funding remains consistent across products.
Basic Eligibility Thresholds
Minimum requirements typically include:
- Time in business: At least one year of operation
- Annual revenue: Minimum of $100,000 in gross sales
- Credit score: Personal credit score of 600 or higher (though higher scores improve terms)
- Bank account: Active business checking account for at least three months
- Legal structure: Must be a for-profit business entity
These baseline criteria screen for businesses with established operations and demonstrated revenue generation. The requirements are generally less stringent than traditional bank loans, which often demand multiple years in business, higher revenue thresholds, and stronger credit profiles.
Underwriting Factors Beyond Minimums
OnDeck's algorithm evaluates numerous factors to determine approval and pricing:
- Revenue trends showing growth or stability
- Cash flow patterns indicating ability to service debt
- Industry classification and associated risk profiles
- Credit history including business and personal credit
- Banking behavior reflecting deposit regularity and account management
- Outstanding debt and existing payment obligations
This multifactor analysis allows OnDeck funding to approve businesses that might not qualify for conventional bank loans, though it also means pricing varies significantly based on perceived risk. According to OnDeck's own reporting on small business trends, the companies they serve span diverse industries with varying credit profiles, reflecting this flexible underwriting approach.
The OnDeck Funding Application and Approval Process
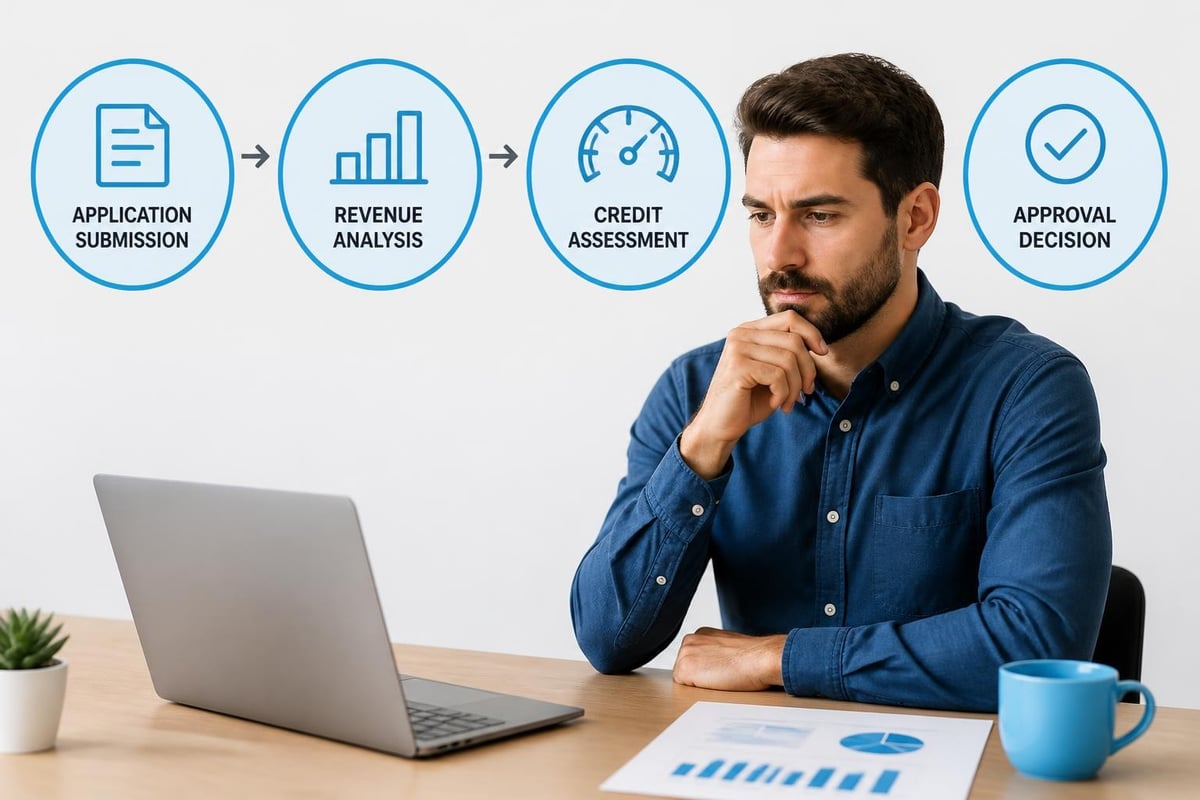
One of the distinguishing features of ondeck funding is the streamlined application experience designed for speed and efficiency. The digital-first process contrasts sharply with traditional bank lending procedures.
Step-by-Step Application Journey
Initial application requires basic information:
- Business legal name and DBA
- Federal Tax ID (EIN)
- Contact information and ownership details
- Requested funding amount
- Brief business description
This initial step typically takes 10-15 minutes. OnDeck then requests access to business bank account data, either through direct read-only integration or by uploading bank statements.
Document submission may include:
- Three to six months of business bank statements
- Driver's license or identification
- Business formation documents (if requested)
- Tax returns (for larger loan amounts)
The technology platform analyzes submitted data in real-time, often generating preliminary decisions within hours. Many applicants receive formal approval or decline notifications the same business day.
Funding timeline proceeds quickly once approved:
- Review and accept loan agreement and terms
- Complete any final verification steps
- Receive funds via ACH transfer
- Begin automated repayment schedule
This compressed timeline makes ondeck funding particularly attractive for businesses facing time-sensitive opportunities or urgent capital needs.
Costs, Pricing, and Total Repayment Considerations
Understanding the true cost of OnDeck funding requires looking beyond the advertised interest rate to the total repayment amount and effective annual percentage rate (APR). OnDeck uses a factor rate pricing model for term loans rather than traditional interest rates.
Factor Rate vs. Interest Rate
Factor rates express the total cost as a multiplier. For example, a factor rate of 1.25 on a $50,000 loan means total repayment of $62,500 ($50,000 × 1.25 = $62,500), representing $12,500 in financing costs.
The equivalent APR depends on the repayment term:
| Loan Amount | Factor Rate | Total Repayment | Term | Approximate APR |
|---|---|---|---|---|
| $50,000 | 1.20 | $60,000 | 12 months | 35-40% |
| $50,000 | 1.25 | $62,500 | 18 months | 25-30% |
| $50,000 | 1.30 | $65,000 | 24 months | 22-27% |
These rates significantly exceed traditional bank loan costs but reflect the speed, convenience, and accessibility ondeck funding provides to businesses that may not qualify for bank financing.
Fee Structures and Additional Costs
Beyond the core cost of capital, OnDeck funding may include:
- Origination fees: Typically built into the factor rate
- Draw fees: On lines of credit when accessing funds
- Late payment fees: If scheduled payments fail
- NSF fees: For insufficient funds on payment dates
The Consumer Financial Protection Bureau's regulations now require enhanced disclosure from many small business lenders, improving transparency around total costs and terms.
Strategic Use Cases for OnDeck Funding
OnDeck funding serves specific business scenarios more effectively than others. Recognizing when this type of financing aligns with business needs versus when alternatives might be superior is crucial for making cost-effective capital decisions.
Optimal Applications
Time-sensitive opportunities represent ideal ondeck funding use cases:
- Inventory purchases to capture seasonal demand
- Equipment acquisition when current machinery fails
- Marketing campaigns during peak business periods
- Emergency repairs or unexpected operational needs
- Bridge financing while awaiting receivables or contracts
In these scenarios, the speed and certainty of OnDeck funding can justify the higher cost. The revenue generated or expenses avoided often exceed the financing premium.
Revenue-generating investments also suit this financing model:
- Marketing initiatives with measurable ROI
- Equipment that increases production capacity
- Technology upgrades improving operational efficiency
- Inventory expansion for proven product lines
- Working capital for fulfilling large orders
When capital deployment generates revenue quickly, the daily or weekly repayment structure aligns well with incoming cash flow.
Less Suitable Scenarios
Certain business situations call for alternative financing approaches:
- Long-term capital investments with slow ROI timelines
- Debt refinancing where lower-cost options exist
- Speculative ventures without proven revenue models
- Business launch costs for brand-new operations
- General operating expenses that don't generate revenue
For these needs, businesses might explore traditional bank loans, SBA financing, equipment leasing, or equity investments instead of ondeck funding.
Comparing OnDeck Funding to Alternative Financing Options
Small businesses in 2026 have access to numerous financing alternatives. Understanding how ondeck funding compares across key dimensions helps business owners select the most appropriate capital source.
Traditional Bank Loans
Advantages of bank loans:
- Lower interest rates (typically 6-12% APR)
- Longer repayment terms (up to 10+ years)
- Larger loan amounts available
- Monthly payment schedules
- Relationship banking benefits
Advantages of OnDeck funding:
- Faster approval and funding
- Less stringent credit requirements
- Shorter operating history accepted
- Simpler documentation requirements
- More predictable approval process
SBA Loan Programs
SBA-backed loans offer government guarantees that reduce lender risk, enabling favorable terms for qualified borrowers. However, the application process is lengthy and documentation requirements extensive. OnDeck funding provides capital in days versus the months often required for SBA loans, making it preferable for urgent needs despite higher costs.
Merchant Cash Advances
Merchant cash advances (MCAs) purchase future receivables at a discount, with repayment tied to daily credit card sales. While similar to ondeck funding in speed and accessibility, MCAs typically carry even higher costs and less predictable repayment amounts. OnDeck's fixed repayment structure provides greater budgeting certainty compared to percentage-based MCA payments.
Research indicates that fintech automation has expanded credit access for underserved business segments, though questions remain about pricing equity and long-term borrower outcomes across different automated lending platforms.
The Broader Market Context for Alternative Business Lending
OnDeck funding exists within a rapidly evolving small business finance ecosystem. Multiple factors shape how businesses access capital and what options are available in 2026.
Regulatory Developments
Enhanced disclosure requirements and data reporting obligations are reshaping the alternative lending landscape. Small business lenders now face increased scrutiny around fair lending practices, pricing transparency, and borrower outcomes. These changes aim to protect business borrowers while maintaining credit availability.
The FinRegLab market context report documents how the small business lending market has evolved since the COVID-19 pandemic, with particular attention to underserved business segments and emerging regulatory frameworks.
Competitive Dynamics
OnDeck competes with numerous alternative lenders, each offering variations on revenue-based financing, term loans, and credit lines. Some competitors focus on specific industries, geographic regions, or business profiles. This competition generally benefits borrowers through:
- Product innovation creating more tailored financing structures
- Pricing pressure as lenders compete for quality borrowers
- Service improvements enhancing the borrower experience
- Technology advancement streamlining application and servicing
Business owners should compare multiple ondeck funding alternatives to ensure they secure optimal terms for their specific situation.
Technology and Data Integration
Modern business lending increasingly relies on alternative data sources beyond traditional credit reports. OnDeck and similar platforms analyze:
- Real-time bank account activity
- Accounting software data
- E-commerce platform sales
- Payment processor information
- Industry benchmarking metrics
This data-rich underwriting enables faster decisions and may improve access for businesses with thin credit files but strong operational performance.
Managing OnDeck Funding Throughout the Loan Lifecycle
Successfully using ondeck funding extends beyond approval and initial funding. Effective management throughout the repayment period ensures positive outcomes and preserves future borrowing capacity.
Repayment Planning and Cash Flow Management
Daily or weekly payments require consistent cash flow monitoring:
- Ensure sufficient account balances before scheduled debits
- Account for payment obligations in cash flow projections
- Monitor business performance against repayment capacity
- Communicate proactively if payment difficulties arise
- Consider accelerated repayment when cash flow permits
Automated payments simplify the process but demand vigilant account management to avoid NSF fees and potential default.
Renewal and Relationship Building
OnDeck often offers renewal opportunities to borrowers with strong payment histories. These renewals may provide:
- Additional capital before full repayment of existing loans
- Improved terms reflecting demonstrated creditworthiness
- Streamlined approval based on existing relationship
- Graduated access to larger amounts over time
Building a positive track record with ondeck funding can create a reliable capital source for ongoing business needs, though business owners should regularly reassess whether continued use remains cost-effective versus emerging alternatives.
Exit Strategies and Alternative Refinancing
As businesses mature and strengthen their financial profiles, transitioning from ondeck funding to lower-cost alternatives becomes strategic. Businesses should:
- Monitor credit score improvements enabling bank qualification
- Build banking relationships supporting future loan applications
- Document business growth and financial stability
- Explore SBA programs as operating history extends
- Consider equipment financing or asset-based lending for specific purchases
Using OnDeck funding as a bridge to more favorable financing represents sound financial management rather than viewing it as a permanent capital source.
Industry-Specific Considerations for OnDeck Funding
Different industries face unique financing challenges and opportunities when considering ondeck funding. Understanding industry-specific factors helps businesses evaluate fit and optimize application strategies.
Retail and E-Commerce
Seasonal inventory needs align well with OnDeck's fast funding and revenue-based repayment. Retailers can:
- Finance inventory purchases ahead of peak seasons
- Leverage rapid funding for trending product opportunities
- Match repayment schedules to sales cycles
- Access additional capital for marketing during high-volume periods
The daily repayment structure works particularly well for businesses with consistent transaction volumes.
Restaurants and Hospitality
Equipment replacement and renovation projects represent common use cases in food service. OnDeck funding provides:
- Quick capital for equipment failures requiring immediate replacement
- Renovation financing for appearance updates or expansion
- Working capital for seasonal staffing increases
- Marketing budgets for new location launches
However, restaurants should carefully model repayment capacity given the industry's thin profit margins and variable cash flow.
Service-Based Businesses
Professional services and B2B companies may find ondeck funding less optimal due to:
- Longer accounts receivable cycles creating cash flow gaps
- Project-based revenue creating uneven cash flow
- Lower transaction volumes reducing daily payment feasibility
- Different working capital patterns than retail businesses
Service businesses should carefully assess payment schedule compatibility with their specific cash flow patterns before committing to OnDeck funding.
Due Diligence and Decision-Making Framework
Before pursuing ondeck funding, business owners should complete thorough analysis ensuring this financing choice serves their best interests.
Pre-Application Assessment
Evaluate actual capital needs:
- Quantify the specific amount required
- Document the intended use and expected ROI
- Project revenue impact and repayment capacity
- Consider timing requirements and urgency
- Assess alternatives and comparative costs
Review qualification likelihood:
- Check personal and business credit scores
- Calculate annual revenue and average monthly sales
- Gather recent bank statements for preliminary review
- Identify any potential red flags in financial history
- Confirm minimum eligibility thresholds
Total Cost Analysis
Calculate the true cost of ondeck funding:
| Analysis Element | Calculation Method |
|---|---|
| Total repayment | Loan amount × factor rate |
| Finance charges | Total repayment - loan amount |
| Effective APR | Use online calculators or request disclosure |
| Daily payment | Total repayment ÷ number of business days |
| ROI requirement | Finance charges ÷ investment return |
Compare these costs against alternative financing options and the expected return from capital deployment.
Long-Term Impact Consideration
Think beyond immediate capital needs:
- How does this financing affect cash flow for the loan term?
- Will repayment obligations constrain future growth investments?
- Does the cost justify the speed and convenience benefits?
- Are there lower-cost alternatives available with acceptable timelines?
- How will this financing affect future borrowing capacity?
Working with financing advisors who understand multiple capital sources can help businesses navigate these complex trade-offs and identify optimal solutions for their specific circumstances.
OnDeck funding represents a valuable tool in the small business financing toolkit, offering speed, accessibility, and flexibility that traditional lenders often cannot match. However, the higher costs demand careful evaluation of alternatives and strategic deployment toward revenue-generating opportunities that justify the financing premium. Enterprise Finest Solutions helps business owners navigate the full spectrum of financing options, connecting you with lenders and capital sources aligned with your revenue performance, industry, and specific funding needs to support sustainable business growth.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.