Kapitus Funding: What Small Businesses Need to Know in 2026
Explore Kapitus funding options, underwriting, terms, and alternatives. Learn how this alternative lender serves small businesses in 2026.
Small businesses seeking capital in 2026 face a landscape transformed by technology, data analytics, and alternative lending models. Among the providers reshaping access to working capital stands Kapitus, a direct lender that has carved out a significant position in the revenue-based financing and merchant cash advance markets. Understanding how kapitus funding works, who it serves, and how it compares to traditional financing can help business owners make informed decisions about their capital needs. This comprehensive guide examines the structure, benefits, considerations, and practical implications of working with this prominent alternative lender.
Understanding the Kapitus Funding Model
Kapitus operates as a direct lender specializing in fast, revenue-based financing solutions for small and medium-sized businesses. Unlike traditional bank loans that emphasize credit scores and collateral, kapitus funding focuses heavily on a business's daily revenue streams and overall financial performance. This approach opens doors for established businesses that may not qualify for conventional bank financing but demonstrate consistent cash flow and operational stability.
The core products in the kapitus funding portfolio include working capital advances, business lines of credit, and term loans designed for rapid deployment. According to NerdWallet's independent review, Kapitus typically funds businesses seeking between $5,000 and $500,000, with approval decisions often rendered within 24 to 48 hours and funding completed within days rather than weeks.
Revenue-Based Underwriting Approach
The distinguishing characteristic of kapitus funding lies in its underwriting methodology. Rather than requiring extensive documentation, multi-year tax returns, or perfect credit profiles, Kapitus evaluates applicants primarily through:
- Daily revenue analysis: Assessment of bank account deposits and payment processing history
- Time in business: Typically requiring at least six months to one year of operational history
- Industry classification: Evaluation of business sector and associated risk factors
- Financial stability: Review of cash flow patterns, overdrafts, and account health
This streamlined approach enables kapitus funding decisions to move quickly, addressing one of the most common pain points for small businesses: the time lag between identifying a capital need and securing financing.
Kapitus Funding Products and Terms
Kapitus structures its financing products to align with different business needs and repayment capabilities. Understanding the nuances between these offerings helps business owners select the most appropriate solution.
| Product Type | Typical Range | Repayment Structure | Best For |
|---|---|---|---|
| Working Capital Advance | $5,000 - $500,000 | Daily/weekly fixed payments | Short-term needs, inventory, payroll |
| Business Line of Credit | Varies by qualification | Draw and repay as needed | Ongoing or seasonal capital needs |
| Term Loan | $10,000 - $250,000 | Fixed periodic payments | Equipment, expansion, one-time projects |
Payment Structure and Factor Rates
Kapitus funding typically employs factor rates rather than traditional annual percentage rates (APR). A factor rate represents a multiplier applied to the borrowed amount to determine total repayment. For example, a $50,000 advance with a 1.25 factor rate would require $62,500 in total repayment, regardless of how quickly the business pays it back.
Key characteristics of kapitus funding terms:
- Factor rates generally range from 1.15 to 1.50, depending on business qualifications
- Repayment periods commonly span 3 to 18 months
- Daily or weekly automatic withdrawals based on a fixed percentage of revenue or a fixed dollar amount
- No prepayment penalties in most product structures
This structure provides predictability for both lender and borrower, though it's important to note that factor rates can translate to higher effective APRs compared to traditional bank loans, particularly for longer-term advances.
The Application and Approval Process
The streamlined nature of kapitus funding applications represents one of its primary competitive advantages. Business owners seeking capital can typically complete the entire process in three to five business days, a stark contrast to the weeks or months required by traditional commercial banks.
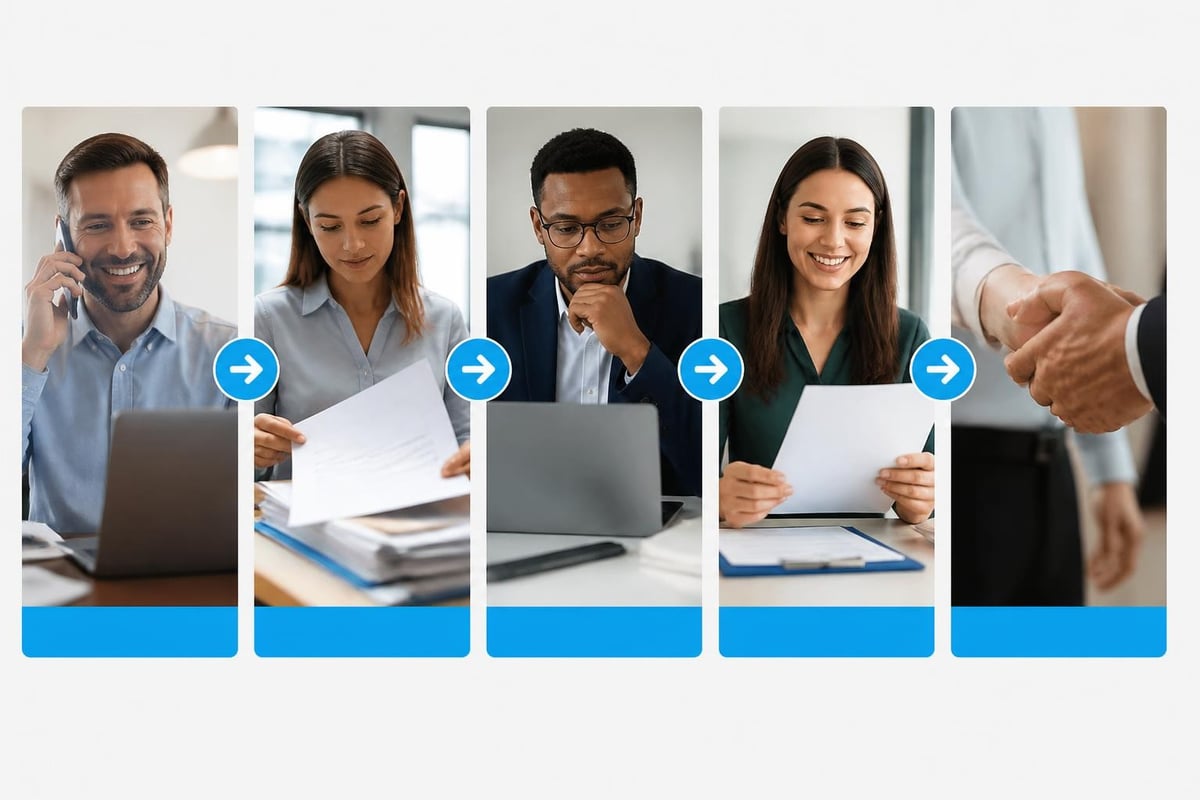
Step-by-Step Application Journey
- Initial inquiry and pre-qualification: Business owners submit basic information about their company, time in business, and funding needs
- Documentation submission: Provide recent bank statements (typically 3-6 months), processing statements if applicable, and business formation documents
- Underwriting review: Kapitus analysts evaluate revenue patterns, account health, and business stability
- Offer presentation: Approved applicants receive funding offers detailing amount, factor rate, term, and payment structure
- Contract execution and funding: Upon acceptance, funds typically arrive via ACH transfer within 1-3 business days
According to official Kapitus communications, the company has funded over $2 billion to small businesses since its founding, demonstrating significant market presence in the alternative lending space.
Who Benefits Most from Kapitus Funding
While kapitus funding serves a broad spectrum of small businesses, certain business profiles and situations align particularly well with this financing approach. Understanding these ideal scenarios helps business owners determine whether this capital source matches their specific circumstances.
Ideal Candidate Profiles
Established businesses with consistent revenue form the core target market for kapitus funding. Retailers processing $10,000 to $100,000 monthly, service businesses with predictable cash flow, and restaurants with steady sales patterns often find this funding model accessible and practical. The revenue-based underwriting means that businesses demonstrating financial momentum can access capital even with imperfect credit histories.
Time-sensitive opportunities represent another strong use case. When a business needs to purchase inventory for peak season, capitalize on a bulk-purchase discount, or address an unexpected equipment failure, the speed of kapitus funding provides strategic value. The opportunity cost of waiting weeks for bank approval may exceed the premium paid in factor rates.
Businesses ineligible for traditional financing frequently turn to kapitus funding as a practical alternative. Companies less than two years old, businesses in industries banks consider high-risk, or those with credit challenges that preclude conventional loans may find Kapitus an accessible capital source.
Common Applications and Use Cases
- Inventory financing: Purchasing seasonal stock, taking advantage of supplier discounts, or expanding product lines
- Marketing campaigns: Funding digital advertising, direct mail campaigns, or promotional activities with measurable ROI
- Equipment repairs or replacement: Addressing critical operational needs without depleting operating reserves
- Cash flow management: Bridging gaps between receivables and payables, covering payroll during slower periods
- Business expansion: Opening new locations, renovating existing facilities, or launching new service offerings
Enterprise Finest Solutions helps businesses explore working capital financing solutions through a network of funding partners, including options that serve similar business profiles and capital needs as kapitus funding products, ensuring business owners can compare multiple approaches to securing growth capital.
Capital Markets Activity and Financial Strength
The stability and backing of a lender matter significantly when businesses establish financing relationships. Kapitus has demonstrated institutional credibility through its capital markets activity and securitization transactions.
In late 2024, Kapitus completed a $250 million securitization backed by small business receivables, simultaneously upsizing its corporate credit facility to $95 million. This transaction represented the company's ninth asset-backed securitization and demonstrated continued institutional investor confidence in the kapitus funding model and loan performance.
Why securitization matters to borrowers:
- Provides evidence of loan quality and performance standards
- Demonstrates access to institutional capital markets
- Suggests financial stability and operational sustainability
- Indicates third-party validation of underwriting practices
These capital markets activities position Kapitus among the more established players in the alternative small business lending sector, distinguishing it from undercapitalized or inconsistent funding sources.
Legal Considerations and Enforcement Practices
Understanding the legal framework surrounding kapitus funding helps business owners enter these arrangements with full awareness of their obligations and the lender's enforcement mechanisms. Court records and public filings provide insight into how Kapitus structures its agreements and pursues remedies when borrowers default.
Contract Structure and Security Interests
Kapitus typically structures its advances as future receivables purchases rather than traditional loans. This legal distinction affects several aspects of the relationship:
| Aspect | Traditional Loan | Receivables Purchase (Kapitus Model) |
|---|---|---|
| Regulatory classification | Lending transaction | Commercial purchase agreement |
| Security interest | Traditional lien/collateral | Personal guarantee, UCC filing |
| Interest rate disclosure | Required APR disclosure | Factor rate (not technically "interest") |
| Default remedies | Foreclosure, repossession | Collection on purchased receivables |
Federal court documents, including bankruptcy proceedings involving Kapitus, reveal that the company typically secures personal guarantees from business owners and files UCC-1 financing statements to establish priority in business assets.
Collection and Default Scenarios
Court opinions from various jurisdictions provide factual context about kapitus funding enforcement. A Western District of Texas bankruptcy opinion and a Kansas bankruptcy court decision illustrate how Kapitus pursues collections through legal channels when businesses default, including claims in bankruptcy proceedings and enforcement of personal guarantees.
Key takeaways from legal proceedings:
- Personal guarantees make business owners individually liable for repayment
- Daily ACH withdrawals continue automatically until satisfied
- Default can trigger acceleration of remaining balance
- Bankruptcy does not automatically discharge receivables purchase obligations
- Legal fees and collection costs typically become borrower's responsibility
These realities underscore the importance of carefully evaluating repayment capacity before accepting kapitus funding offers.
Comparing Kapitus to Alternative Funding Sources
Business owners evaluating kapitus funding should understand how it positions relative to other capital sources available in 2026. Each financing type serves different business scenarios and carries distinct advantages and limitations.
Traditional Bank Loans
Advantages over kapitus funding:
- Significantly lower interest rates and borrowing costs
- Longer repayment terms (typically 3-10 years)
- May offer larger loan amounts for qualified businesses
- Builds traditional business credit history
Disadvantages compared to kapitus funding:
- Stringent credit requirements (typically 680+ credit score)
- Extensive documentation requirements
- Slower approval process (weeks to months)
- Collateral requirements for larger amounts
- Less accessible for newer or non-traditional businesses
SBA Loans
Small Business Administration guaranteed loans offer government-backed financing with favorable terms but rigorous qualification standards.
When SBA loans make more sense than kapitus funding:
- Businesses with strong credit profiles and extensive documentation
- Capital needs exceeding $250,000
- Long-term investments requiring 10+ year amortization
- Real estate purchases or major equipment acquisitions
When kapitus funding makes more sense than SBA:
- Time-sensitive capital needs requiring rapid deployment
- Businesses with credit challenges or limited operating history
- Smaller amounts ($5,000-$150,000) with shorter payback horizons
- Seasonal or short-term working capital needs
Competitor Alternative Lenders
The alternative lending market includes numerous competitors to Kapitus, each with slightly different underwriting criteria, product structures, and market positioning. Businesses should compare multiple options to identify the best fit for their specific situation and qualifications.
Key comparison factors:
- Factor rates and total cost of capital
- Funding speed and process efficiency
- Minimum and maximum funding amounts
- Industry restrictions and preferences
- Repayment flexibility and structure
- Customer service and relationship management
Strategic Considerations Before Applying
Approaching kapitus funding strategically maximizes value and minimizes risk. Business owners should evaluate several critical factors before initiating applications.
Return on Investment Analysis
The fundamental question for any borrowed capital: will the use of funds generate returns exceeding the cost of financing? With factor rates potentially translating to 15%-50% effective APRs, kapitus funding requires clear, measurable deployment strategies.
High-ROI applications:
- Inventory purchases with 2x+ markup margins
- Marketing campaigns with proven customer acquisition costs
- Equipment purchases enabling new revenue streams
- Contract fulfillment requiring upfront capital investment
Lower-ROI applications (proceed cautiously):
- Covering operating losses without addressing root causes
- Discretionary upgrades without revenue impact
- Refinancing existing debt at higher costs
- General operating expenses without specific deployment plan
Cash Flow Impact Assessment
Daily or weekly automatic withdrawals affect cash flow differently than monthly loan payments. Model the impact of these deductions on your operating capital before accepting offers.
Calculate:
- Current average daily bank balance
- Proposed daily withdrawal amount
- Resulting available operating capital
- Buffer needed for unexpected expenses or revenue fluctuations
- Whether remaining cash flow supports ongoing operations
Businesses operating with thin margins or inconsistent revenue patterns may find the rigidity of automatic withdrawals challenging during slower periods.
Alternative Exploration
Before committing to kapitus funding, ensure you've explored all practical alternatives. The regulatory environment continues to evolve, with entities like the Consumer Financial Protection Bureau increasing scrutiny of various financial services sectors, highlighting the importance of working with established, reputable providers.
Consider:
- Business credit cards with promotional APR periods
- Lines of credit from community banks or credit unions
- Equipment financing specifically for asset purchases
- Vendor financing or trade credit terms
- Angel investors or crowdfunding for growth capital
- Revenue-based financing from multiple providers for comparison
Industry-Specific Applications
Different industries experience varying degrees of success with kapitus funding based on revenue patterns, cash flow predictability, and seasonal dynamics.
Retail and E-Commerce
Retailers benefit from kapitus funding when purchasing seasonal inventory, expanding product lines, or capitalizing on bulk-purchase opportunities. The correlation between inventory investment and sales revenue creates a natural alignment with revenue-based repayment structures.
Optimal scenarios:
- Pre-season inventory purchases with 60-120 day sales cycles
- Product launches requiring initial stock investment
- Fulfillment of large wholesale orders
Food Service and Hospitality
Restaurants and hospitality businesses frequently use kapitus funding for equipment repairs, facility improvements, or marketing initiatives. The daily revenue focus aligns well with businesses processing consistent credit card transactions.
Common applications:
- Kitchen equipment replacement or upgrades
- Dining room renovations or expansions
- Marketing campaigns for grand openings or rebranding
- Bridging seasonal revenue gaps in tourist-dependent locations
Professional Services
Consulting firms, healthcare practices, and professional service providers may find kapitus funding useful for practice expansion, technology investments, or marketing initiatives, though the repayment structure requires careful cash flow planning.
Suitable uses:
- Office build-outs or relocations
- Technology infrastructure upgrades
- Staff hiring and training investments
- Marketing and business development campaigns
Managing Kapitus Funding Relationships
Successfully navigating a kapitus funding arrangement requires proactive financial management and clear communication.
Best Practices for Borrowers
- Maintain detailed cash flow projections: Track actual versus projected revenue weekly to identify potential payment challenges early
- Communicate proactively: Contact Kapitus immediately if you anticipate payment difficulties rather than waiting for default
- Monitor bank account balances: Ensure sufficient funds exist for daily withdrawals to avoid overdraft fees and default triggers
- Document fund deployment: Track exactly how borrowed capital is deployed and measure return on investment
- Plan for payoff: Consider accelerating repayment during strong revenue periods to reduce total cost
Warning Signs and Risk Mitigation
Certain situations should trigger caution when considering or managing kapitus funding:
- Stacking multiple advances: Taking multiple simultaneous advances from different lenders compounds daily withdrawal burdens
- Using funding for non-productive expenses: Borrowing for operating losses rather than growth initiatives
- Ignoring underlying business problems: Using capital to mask rather than address fundamental business challenges
- Failing to model repayment impact: Accepting offers without calculating actual cash flow implications
Kapitus funding represents a significant option in the alternative lending landscape, offering speed and accessibility for businesses that meet its revenue-focused criteria. Understanding the structure, costs, and implications of these financing arrangements enables business owners to make informed decisions aligned with their strategic objectives and financial capacity. Enterprise Finest Solutions helps small and medium-sized businesses navigate the complex landscape of funding options, connecting business owners with financing solutions tailored to their revenue performance, industry, and capital needs.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.


