iBusiness Funding: A Guide to Modern Capital Solutions
Explore ibusiness funding strategies for 2026. Learn how digital-first capital solutions help SMBs access flexible financing faster and grow.
The landscape of business financing has transformed dramatically over the past decade, with digital platforms and alternative lenders reshaping how entrepreneurs access capital. The term "ibusiness funding" reflects this evolution, representing the intersection of technology, data analytics, and financial services that now defines modern business financing. For small and medium-sized enterprises navigating growth challenges in 2026, understanding these digital-first funding solutions has become essential for maintaining competitive advantage and operational flexibility.
The Evolution of Digital Business Financing
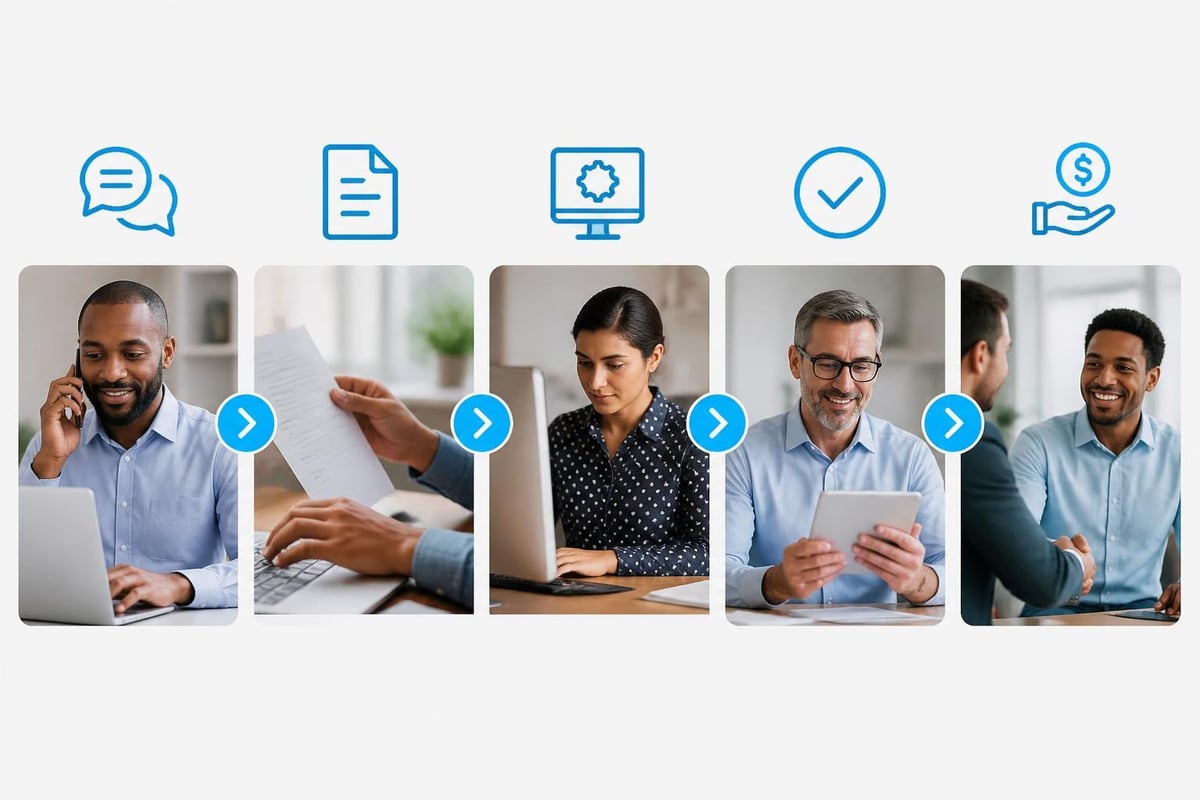
Traditional bank lending has long dominated the business financing sector, but approval rates, lengthy processing times, and rigid requirements have created significant gaps in capital access. The emergence of ibusiness funding platforms addresses these limitations by leveraging technology to streamline applications, accelerate underwriting, and expand eligibility criteria beyond conventional credit metrics.
Key advantages of digital funding platforms include:
- Application completion in minutes rather than hours or days
- Automated underwriting that evaluates business performance holistically
- Funding decisions within 24-48 hours compared to weeks or months
- Flexible repayment structures aligned with revenue patterns
- Reduced documentation requirements through data integration
The FDIC's 2024 Small Business Lending Survey reveals that while traditional banks remain important capital sources, alternative lenders now account for a growing share of small business financing, particularly for businesses with annual revenues under $5 million.
How Technology Transforms Capital Access
Modern ibusiness funding platforms utilize sophisticated algorithms that analyze hundreds of data points to assess creditworthiness. Rather than relying solely on personal credit scores and collateral, these systems evaluate:
- Revenue trends across multiple months or years
- Bank account activity showing cash flow patterns
- Industry benchmarks for performance comparison
- Customer retention metrics indicating business stability
- Seasonal variations that affect repayment capacity
This data-driven approach enables lenders to make informed decisions about businesses that might not meet traditional lending criteria but demonstrate strong operational performance and growth potential.
Revenue-Based Financing Models
Among the most significant innovations in ibusiness funding, revenue-based financing structures have gained substantial traction. These arrangements tie repayment to business performance, creating alignment between lender and borrower interests that traditional term loans cannot match.
Understanding Merchant Cash Advances
Merchant cash advances represent one popular revenue-based funding option. Businesses receive a lump sum in exchange for a percentage of future credit card sales or daily revenue. The repayment amount adjusts automatically based on sales volume, providing built-in flexibility during slower periods.
| Feature | Merchant Cash Advance | Traditional Term Loan |
|---|---|---|
| Approval speed | 1-3 business days | 2-8 weeks |
| Primary qualifier | Revenue history | Credit score & collateral |
| Repayment | % of daily sales | Fixed monthly payment |
| Flexibility | Adjusts with revenue | Fixed regardless of performance |
| Documentation | Minimal | Extensive |
This structure particularly benefits businesses with seasonal fluctuations or variable revenue patterns. Restaurants, retail shops, and service businesses often find revenue-based ibusiness funding more manageable than rigid monthly loan payments.
Alternative Funding Options for Growing Businesses
The ibusiness funding ecosystem encompasses diverse capital solutions beyond merchant cash advances. Entrepreneurs should understand the full spectrum of options available through digital platforms.
Lines of Credit
A business line of credit provides revolving access to capital, allowing businesses to draw funds as needed up to a predetermined limit. Interest accrues only on the amount used, making this option cost-effective for managing cash flow gaps, inventory purchases, or unexpected expenses.
Common uses for business lines of credit include:
- Bridging gaps between accounts receivable and payable
- Purchasing seasonal inventory before peak sales periods
- Covering payroll during temporary revenue dips
- Funding marketing campaigns or promotional activities
- Managing equipment repairs or facility maintenance
The SBA offers additional funding opportunities that complement commercial lines of credit, including microloans and specialized programs for specific industries or demographics.
Invoice Financing Solutions
Businesses with outstanding invoices can unlock working capital through invoice financing or factoring arrangements. These ibusiness funding solutions advance 70-90% of invoice value immediately, with the remainder (minus fees) paid when customers settle their accounts.
This approach works particularly well for B2B companies with net-30, net-60, or net-90 payment terms that create cash flow constraints. Rather than waiting months for payment, businesses can access capital within days to fund operations, take on new projects, or invest in growth initiatives.
Equipment Financing in the Digital Age
Capital-intensive businesses requiring machinery, vehicles, or technology can leverage specialized equipment financing channels. These ibusiness funding arrangements use the purchased equipment as collateral, often enabling higher approval rates and more favorable terms than unsecured financing.
Modern equipment financing platforms have streamlined the process considerably. Business owners can:
- Submit applications online with minimal documentation
- Receive preliminary approval within hours
- Compare multiple financing offers simultaneously
- Complete transactions digitally without in-person meetings
- Access funds and acquire equipment within days
The tax implications of equipment financing deserve careful consideration. According to the IRS Tax Guide for Small Business, businesses may deduct interest expenses and depreciation, potentially creating significant tax advantages. Section 179 deductions may allow businesses to deduct the full purchase price of qualifying equipment in the year of acquisition, subject to annual limits.
Evaluating iBusiness Funding Providers
Not all digital lending platforms offer equal value, service quality, or transparency. Business owners should conduct thorough due diligence before committing to any funding arrangement.
Key Evaluation Criteria
Transparency and disclosure rank among the most critical factors. Reputable ibusiness funding providers clearly communicate:
- Total cost of capital (including all fees and interest)
- Repayment terms and schedules
- Prepayment penalties or restrictions
- Default consequences and remedies
- Funding timeline from approval to disbursement
Customer service accessibility matters significantly when problems arise or questions emerge. Evaluate whether providers offer dedicated account representatives, responsive support channels, and clear escalation procedures.
Industry experience indicates whether a lender understands your business model, seasonal patterns, and specific capital needs. Some ibusiness funding platforms specialize in particular sectors like restaurants, healthcare, retail, or professional services.
| Red Flags | Positive Indicators |
|---|---|
| Reluctance to disclose total costs | Clear fee schedules and APR calculations |
| Pressure to sign quickly | Reasonable review period |
| No online presence or reviews | Established track record and testimonials |
| Upfront fees before approval | Fees deducted from funding or built into repayment |
| Vague repayment terms | Detailed repayment schedules and examples |
Research from the Kroll Bond Rating Agency on small-business asset-backed securities reveals how institutional investors increasingly participate in the small business lending market, driving both competition and standardization that benefit borrowers.
Strategic Capital Deployment
Securing ibusiness funding represents only the first step; strategic deployment determines whether capital investment generates positive returns. Business owners should develop clear plans for fund utilization that align with growth objectives and operational needs.
High-Impact Capital Uses
Revenue-generating investments should take priority in most cases. Expenditures that directly increase sales, improve margins, or expand capacity typically deliver the strongest returns:
- Marketing campaigns targeting new customer segments
- Sales team expansion or commission structure optimization
- Product line extensions or service offerings
- Geographic expansion into new markets
- Technology that enhances customer experience or operational efficiency
Operational efficiency improvements can generate substantial returns through cost reduction and productivity gains. Consider investing in:
- Automation tools that reduce manual labor requirements
- Inventory management systems that minimize carrying costs
- Customer relationship management platforms that improve retention
- Supply chain optimization reducing procurement expenses
- Energy-efficient equipment lowering utility costs
Risk mitigation expenditures may not generate immediate returns but protect business continuity. Building cash reserves, diversifying supplier relationships, or investing in cybersecurity infrastructure can prevent far more costly disruptions.
Regulatory Considerations and Compliance
The ibusiness funding sector operates within a complex regulatory framework that varies by state, funding type, and lender classification. Business owners should understand basic compliance requirements and protections.
State Lending Regulations
Most states regulate lending activities through licensing requirements, interest rate caps (usury laws), and disclosure mandates. Some alternative financing structures, particularly merchant cash advances, may fall outside traditional lending regulations, creating both opportunities and risks.
The Brookings Institution's analysis of federal policy shifts affecting minority-owned businesses highlights how regulatory changes continue reshaping capital access, particularly for underserved business segments.
Documentation and Record Keeping
Proper documentation serves multiple purposes for businesses utilizing ibusiness funding solutions:
- Tax compliance: Interest and fee deductions require proper substantiation
- Financial reporting: GAAP compliance for businesses with external stakeholders
- Future financing: Lenders review how prior capital was deployed and repaid
- Legal protection: Documentation supports claims in disputes
Business owners should maintain organized records including funding agreements, repayment schedules, bank statements showing fund deployment, and correspondence with lenders.
Building Creditworthiness for Better Terms
While ibusiness funding platforms often accommodate businesses with imperfect credit, improving creditworthiness opens access to more favorable terms, lower costs, and higher funding amounts.
Practical Credit-Building Strategies
Consistent revenue growth demonstrates business viability and repayment capacity more effectively than any other factor. Focus on:
- Customer acquisition and retention initiatives
- Pricing optimization to improve margins
- Product or service quality enhancements
- Operational efficiency that reduces costs
Timely repayment of existing obligations builds credibility with both traditional and alternative lenders. Even if current financing carries higher costs, pristine repayment history positions businesses for refinancing at better rates.
Transparent financial management through proper bookkeeping, regular financial statement preparation, and clean separation of business and personal finances signals professional operation that lenders value.
The Library of Congress research guide on small-business financing provides additional resources on building creditworthiness and accessing various capital sources including grants that don't require repayment.
Preparing for Future Funding Needs
Strategic business operators plan capital access before urgent needs arise. Establishing relationships with ibusiness funding providers and maintaining qualification readiness enables faster response to opportunities or challenges.
Building a Funding Roadmap
Forward-thinking businesses develop multi-year capital plans that anticipate:
- Seasonal working capital requirements based on historical patterns
- Growth capital for planned expansion initiatives
- Emergency reserves for unexpected equipment failures or market disruptions
- Opportunity capital to pursue time-sensitive competitive advantages
| Business Stage | Typical Capital Needs | Preferred Funding Types |
|---|---|---|
| Startup (0-2 years) | Operating losses, initial inventory, market entry | Personal savings, friends/family, SBA microloans |
| Growth (2-5 years) | Inventory expansion, hiring, marketing | Revenue-based financing, lines of credit |
| Expansion (5-10 years) | New locations, equipment, acquisitions | Term loans, equipment financing, investor capital |
| Mature (10+ years) | Refinancing, optimization, innovation | Traditional bank products, specialized financing |
Technology Integration and Future Trends
The ibusiness funding landscape continues evolving as technology advances and new entrants bring innovation to capital markets. Several trends are reshaping how businesses access and deploy capital in 2026.
Artificial Intelligence in Underwriting
Machine learning algorithms now analyze alternative data sources including social media presence, online reviews, website traffic, and supply chain relationships. These insights enable more nuanced credit decisions that consider business context beyond traditional metrics.
Embedded finance integrations allow businesses to access capital directly through platforms they already use for operations. Accounting software, e-commerce platforms, and point-of-sale systems increasingly offer integrated financing options that leverage transaction data for instant underwriting.
Blockchain and decentralized finance (DeFi) protocols are beginning to extend into small business lending, though regulatory uncertainty and technical complexity limit mainstream adoption. These systems promise reduced intermediary costs and faster settlement times.
Information about federal programs and grant opportunities can be found through the U.S. Senate's research page on grants, which provides comprehensive guidance on accessing government capital programs.
Risk Management Best Practices
While ibusiness funding provides valuable capital access, borrowing always carries risk. Responsible business operators implement safeguards to ensure financing supports rather than jeopardizes long-term viability.
Avoiding Over-Leverage
Debt service coverage ratio (DSCR) measures whether operating income sufficiently exceeds debt obligations. Most financial advisors recommend maintaining DSCR above 1.25, meaning income exceeds debt service by at least 25%.
Calculate DSCR using this formula: DSCR = Net Operating Income ÷ Total Debt Service
Businesses with DSCR below 1.0 are consuming more cash for debt service than they generate from operations, an unsustainable situation requiring immediate attention.
Matching funding duration to asset life prevents situations where businesses repay financing long after funded assets stop generating returns. Short-term working capital needs should use short-term ibusiness funding solutions, while long-lived equipment justifies longer repayment periods.
Contingency Planning
Prudent businesses maintain contingency plans for repayment challenges:
- Emergency cash reserves covering 3-6 months of essential expenses
- Revenue diversification reducing dependence on single customers or markets
- Flexible cost structures allowing rapid expense reduction if needed
- Lender communication protocols for proactive dialogue during difficulties
- Alternative revenue sources that can be activated quickly
Early communication with ibusiness funding providers when challenges emerge often yields better outcomes than avoiding contact until default becomes inevitable.
Understanding ibusiness funding options empowers business owners to access capital strategically, deploy it effectively, and manage repayment responsibly. The digital transformation of business financing has created unprecedented access to flexible capital solutions that align with modern business realities. Enterprise Finest Solutions connects small and medium-sized businesses with a curated network of funding partners, helping entrepreneurs identify financing solutions that match their revenue patterns, industry requirements, and growth objectives.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.