Champions Funding LLC: Business Financing Insights 2026
Explore champions funding llc's role in business finance. Learn how specialized lenders and CDFI-certified firms shape funding options for SMBs.
The business financing landscape has evolved dramatically over the past decade, with specialized lenders and alternative funding providers playing an increasingly important role in serving small and medium-sized businesses. Among these providers, champions funding llc represents one example of how niche lenders focus on specific market segments and financing products. Understanding how specialized funding firms operate, their regulatory frameworks, and their product offerings helps business owners make informed decisions when exploring capital solutions beyond traditional bank loans. As SMBs seek faster approvals, flexible repayment structures, and revenue-based financing options, examining the broader ecosystem of alternative lenders provides valuable context for evaluating funding opportunities.
The Rise of Specialized Business Lenders
Traditional banks have long dominated commercial lending, but their stringent underwriting requirements, lengthy approval processes, and conservative risk appetite have created significant gaps in the market. Specialized lenders emerged to fill these voids by focusing on specific industries, loan types, or underserved business segments.
Champions funding llc operates within this specialized lending environment, with a focus on non-qualified mortgage (Non-QM) products and community development financial institution (CDFI) designation. According to their official company history, the firm positions itself as a provider of alternative mortgage solutions, demonstrating how specialized lenders carve out distinct niches within the broader financial services industry.
Understanding CDFI Certification
Community Development Financial Institutions represent a unique category of lenders certified by the U.S. Treasury Department. These organizations commit to serving economically distressed communities and providing financial services to underserved populations.
The CDFI Fund maintains public records of certified institutions, including champions funding llc, which appears in official awardee profiles as a certified loan fund. This designation carries several implications:
- Mission-driven lending: CDFIs balance profit with community impact objectives
- Access to federal programs: Eligibility for Treasury grants and favorable financing terms
- Regulatory oversight: Additional reporting requirements and compliance obligations
- Target market focus: Commitment to serving low-income or economically distressed areas
CDFI certification signals a lender's commitment to specific underwriting philosophies and community reinvestment goals, which can influence their product offerings, approval criteria, and borrower relationships.
Product Focus and Market Positioning
Specialized lenders typically concentrate on one or two core product lines rather than offering comprehensive financial services. This focused approach allows them to develop deep expertise, streamline operations, and serve specific borrower needs more effectively than generalist institutions.
Champions funding llc centers its operations on Non-QM mortgage products, according to information available through their correspondent lending platform. Non-QM loans serve borrowers who don't meet conventional mortgage guidelines due to income documentation challenges, credit history issues, or unique property types.
Non-QM vs. Business Financing Products
While champions funding llc focuses primarily on mortgage products, understanding the parallels between Non-QM lending and alternative business financing reveals common themes in specialized lending:
| Feature | Non-QM Mortgages | Alternative Business Financing |
|---|---|---|
| Underwriting | Flexible income verification | Revenue-based assessment |
| Documentation | Bank statements, asset review | Business performance data |
| Speed | Faster than conventional | Often same-week approval |
| Rates | Higher than conforming loans | Higher than bank financing |
| Borrower Profile | Self-employed, complex income | Established revenue, weaker credit |
Both product categories serve borrowers who fall outside traditional lending boxes, rely on alternative data sources for creditworthiness assessment, and typically carry higher costs reflecting increased lender risk.
Regulatory Framework for Alternative Lenders
Alternative lenders operate within a complex regulatory environment that varies by product type, lender structure, and jurisdiction. Recent years have seen increased regulatory attention on transparency, disclosure, and consumer protection in the alternative lending space.
The Consumer Financial Protection Bureau provides comprehensive guidance on small business lending requirements, including detailed FAQs addressing merchant cash advances and revenue-based financing products. These resources clarify lenders' obligations regarding:
- Disclosure requirements: Clear presentation of costs, terms, and repayment schedules
- Data collection: Demographic and business information for fair lending monitoring
- Reporting obligations: Submission of lending data to federal regulators
- Consumer protections: Safeguards against predatory practices and unfair terms
State-Level Registration and Compliance
Beyond federal oversight, alternative lenders must navigate state-by-state licensing requirements. State business registrations provide public accountability and consumer recourse mechanisms. Official state filings, such as those maintained by Rhode Island's Secretary of State, document corporate registrations and operating authorities for entities like champions funding llc.
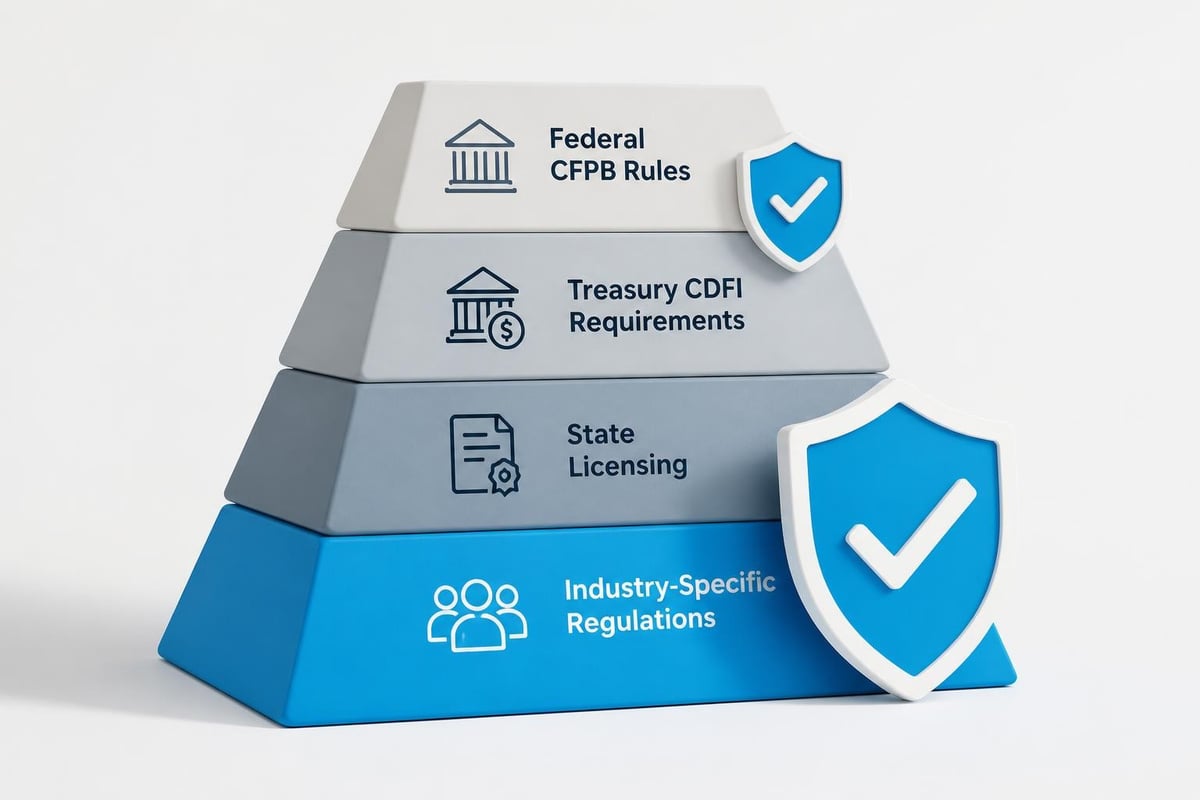
State registration creates a paper trail of corporate good standing, registered agents, and jurisdictional authority, which business borrowers can verify when evaluating potential lenders.
Evaluating Specialized Lenders for Business Funding
Business owners exploring financing options beyond traditional banks should conduct thorough due diligence on specialized lenders. While firms like champions funding llc may focus on specific product lines outside general business financing, the evaluation framework applies broadly across alternative lenders.
Key Assessment Criteria
Corporate transparency and track record matter significantly. Reputable lenders maintain clear websites, provide accessible customer service, and offer detailed product information. Their corporate history, ownership structure, and market tenure provide context for stability and reliability.
Regulatory compliance and certifications signal legitimacy. CDFI designation, state licensing, and industry memberships demonstrate adherence to professional standards. Verified regulatory status protects borrowers from fraudulent operators.
Product-market fit determines whether a lender's offerings align with your business needs. A mortgage-focused lender like champions funding llc serves different purposes than providers specializing in working capital, equipment financing, or merchant cash advances.
Understanding True Costs
Alternative financing typically costs more than traditional bank loans, reflecting higher risk profiles and faster approval processes. The U.S. Treasury Department has highlighted concerns about transparency in small business financing, particularly regarding disclosure of effective interest rates and total repayment amounts.
Business owners should compare offers using consistent metrics:
- Annual Percentage Rate (APR): Annualized cost including fees
- Total repayment amount: Principal plus all fees and interest
- Payment frequency: Daily, weekly, or monthly obligations
- Prepayment penalties: Costs for early repayment
- Collateral requirements: Personal guarantees or business assets
For businesses seeking working capital or revenue-based financing solutions, partnering with a broker specializing in merchant cash advance and revenue-based financing can help navigate multiple lender options and identify terms that match business cash flow patterns.
The Small Business Financing Landscape in 2026
Recent research provides valuable insights into how small businesses access capital and their experiences with various funding sources. The Federal Reserve's Small Business Credit Survey tracks lending patterns, approval rates, and borrower satisfaction across different financing types.
Current Market Trends
Several key trends characterize the 2026 small business financing environment:
Digital-first application processes have become standard. Most alternative lenders now offer fully online applications with automated preliminary approvals within hours. This speed advantage continues to drive businesses toward non-bank lenders despite higher costs.
Revenue-based underwriting increasingly supplements or replaces traditional credit scoring. Lenders analyze bank statements, payment processing data, and business performance metrics to assess repayment capacity, opening access for businesses with strong revenue but weaker credit profiles.
Product diversification among specialized lenders expands borrower options. While champions funding llc focuses on Non-QM mortgages, many alternative lenders now offer multiple products including term loans, lines of credit, equipment financing, and merchant cash advances under single platforms.
Regulatory scrutiny continues intensifying. Federal and state authorities increasingly focus on disclosure clarity, fair lending practices, and protection against predatory terms, particularly in the merchant cash advance sector.
Matching Business Needs to Lender Capabilities
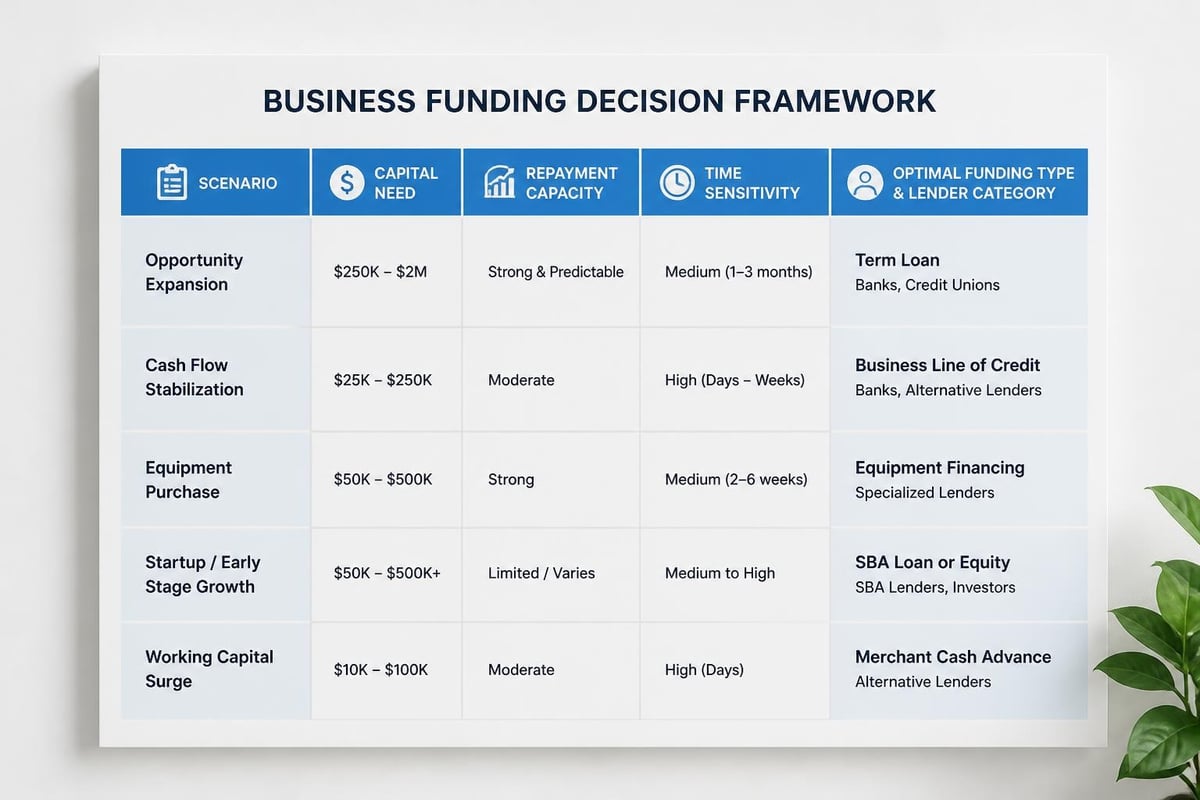
Not all funding sources suit all business situations. The specialized nature of firms like champions funding llc underscores the importance of matching business needs to lender capabilities and product offerings.
Funding Source Selection Framework
| Business Scenario | Optimal Funding Type | Typical Provider |
|---|---|---|
| Equipment purchase | Equipment financing | Specialized equipment lenders |
| Real estate acquisition | Commercial mortgage | Banks, CDFI lenders |
| Working capital needs | Revenue-based financing | Alternative lenders, brokers |
| Seasonal inventory | Line of credit | Banks, online lenders |
| Emergency expenses | Merchant cash advance | Alternative funders |
| Long-term expansion | SBA loan | Banks, CDFI institutions |
Business owners benefit from understanding the distinction between mortgage-focused lenders, equipment financiers, working capital providers, and comprehensive business funding brokers.
When to Consider Specialized vs. Generalist Lenders
Specialized lenders excel when businesses need expertise in niche products, serve specific industries, or require flexible underwriting within a defined category. Champions funding llc, for instance, brings deep Non-QM mortgage expertise valuable for real estate investors or self-employed borrowers with complex income documentation.
Generalist lenders or brokers offer advantages for businesses exploring multiple funding options, comparing terms across product types, or needing guidance on which financing structure best matches their situation. Business funding brokers maintain relationships with numerous lenders and can quickly identify suitable matches.
Due Diligence Best Practices
Before committing to any financing arrangement, business owners should complete thorough verification and comparison processes. These practices protect against predatory lenders and ensure optimal terms.
Verification Steps
- Confirm regulatory status: Check CDFI certification, state licensing, and Better Business Bureau ratings
- Research company background: Review corporate filings, ownership information, and operational history
- Read customer reviews: Examine independent review platforms and complaint databases
- Request written terms: Obtain complete disclosure documents before signing
- Calculate total costs: Determine APR, total repayment, and effective interest rate
- Compare multiple offers: Evaluate at least three financing options
The CFPB's detailed FAQ document provides authoritative guidance on understanding financing terms, comparing offers, and identifying red flags in lending proposals.
Red Flags to Avoid
Pressure tactics suggesting limited-time offers or immediate decisions signal potential problems. Reputable lenders provide adequate time for review and comparison.
Vague cost disclosures that obscure true interest rates, fees, or repayment amounts indicate poor transparency. Legitimate lenders clearly itemize all costs.
Upfront fees before loan approval often characterize scams. Most legitimate lenders collect fees only at closing or deduct them from funded amounts.
Unsolicited offers via email, phone, or mail merit extra scrutiny. While not inherently fraudulent, they require careful verification of the sender's legitimacy.
The Role of CDFI Lenders in Business Ecosystems
CDFI-certified institutions like champions funding llc serve important functions in underserved markets. Their mission-driven approach often provides access to capital in communities where traditional banks limit lending activity.
CDFI Advantages
- Flexible underwriting: Greater willingness to consider alternative credit factors
- Community knowledge: Understanding of local economic conditions and challenges
- Technical assistance: Many CDFIs offer business counseling alongside financing
- Patient capital: Longer-term perspective on borrower success
CDFI Limitations
- Product constraints: Focus on mission-aligned lending may limit product variety
- Capacity restrictions: Smaller capital bases than major banks
- Geographic focus: Service area limitations based on target market definitions
- Eligibility requirements: Borrowers may need to meet specific demographic or location criteria
Business owners in CDFI target markets should explore these lenders as one component of a comprehensive funding search strategy.
Integration with Broader Funding Strategies
Champions funding llc and similar specialized lenders represent individual pieces within a complex funding ecosystem. Smart business owners develop multi-source capital strategies rather than relying on single providers.
Building a Capital Stack
Primary operating capital typically comes from the most affordable, stable sources: traditional bank loans, SBA financing, or investor equity.
Growth capital might include mid-cost options like lines of credit, equipment financing, or revenue-based loans with reasonable terms.
Emergency reserves can involve higher-cost but quickly accessible options like merchant cash advances or short-term working capital advances.
Strategic financing for specific projects might leverage specialized lenders with expertise in particular asset types or transaction structures.
This layered approach optimizes cost while maintaining flexibility and access across different business scenarios.
Future Outlook for Alternative Business Lending
The alternative lending sector continues evolving rapidly, driven by technology innovation, regulatory changes, and shifting borrower expectations. Several trends will likely shape the industry through the remainder of this decade.
Embedded finance integration will bring funding options directly into business software platforms. Accounting systems, payment processors, and e-commerce platforms increasingly offer financing at the point of need.
AI-powered underwriting will accelerate approval speeds and improve risk assessment accuracy. Machine learning models analyzing thousands of data points will enable more nuanced credit decisions.
Regulatory standardization may emerge as federal and state authorities work toward consistent disclosure requirements and consumer protections across product types.
Market consolidation could concentrate the industry as larger players acquire specialized lenders, though niche providers like champions funding llc may maintain distinct positions through deep vertical expertise.
Understanding how specialized lenders operate, their regulatory frameworks, and their market positioning helps business owners make informed capital decisions. Whether exploring CDFI-certified institutions, alternative funding providers, or traditional banks, thorough research and comparison shopping remain essential. Enterprise Finest Solutions helps small and medium-sized businesses navigate this complex landscape by connecting them with appropriate lenders and funding options that match their revenue, performance, and capital requirements.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.