Business Loan Collateral: What Assets Secure Funding
Learn what business loan collateral is, which assets lenders accept, how collateral affects loan terms, and strategies to secure financing in 2026.
When small and medium-sized businesses seek financing, one of the most important questions lenders ask is what assets can secure the loan. Business loan collateral serves as a safety net for lenders, reducing their risk while potentially unlocking better terms and larger amounts for borrowers. Understanding how collateral works, which assets qualify, and how lenders evaluate pledged property can help business owners navigate the funding process with confidence. Whether you're exploring traditional bank loans, asset-based financing, or alternative funding solutions, knowing the fundamentals of collateral requirements will strengthen your position and expand your financing options.
Understanding Business Loan Collateral
Business loan collateral refers to assets a borrower pledges to secure financing, giving the lender the legal right to seize and sell those assets if the borrower defaults on the loan. This security interest is typically formalized through legal documents that create a lien against the pledged property. Collateral creates a secured loan structure, which differs fundamentally from unsecured financing where lenders rely solely on creditworthiness and cash flow.
The use of collateral has grown significantly across commercial lending markets. Lenders view pledged assets as a risk mitigation tool that allows them to extend credit to businesses that might not qualify for unsecured financing based solely on revenue or credit scores.
Key benefits of secured lending include:
- Lower interest rates compared to unsecured options
- Higher loan amounts relative to business size
- Longer repayment terms that improve cash flow management
- Increased approval likelihood for newer or riskier businesses
The value and type of business loan collateral directly influence loan terms. Real estate typically commands the most favorable rates due to its stability and ease of valuation, while inventory or equipment may result in higher rates because of depreciation concerns and liquidation challenges.
Types of Assets Lenders Accept as Collateral
Lenders evaluate a wide range of assets when determining what can secure a business loan. Each asset class carries different risk profiles, liquidation values, and advance rates.
Real Estate and Property
Commercial real estate represents the gold standard of business loan collateral. Buildings, land, warehouses, and office spaces offer stable value and established appraisal methods. Lenders typically advance 70% to 85% of appraised value for commercial property, depending on location, condition, and market demand.
Personal real estate, including a business owner's primary residence or investment properties, can also secure business financing. Many entrepreneurs leverage home equity when their business lacks sufficient commercial assets. However, this approach carries significant personal risk if the business struggles.
Equipment and Machinery
Physical equipment serves as effective collateral across industries. Manufacturing machinery, medical devices, construction equipment, commercial vehicles, restaurant fixtures, and technology infrastructure all qualify. Equipment financing options allow businesses to use the purchased equipment itself as collateral, creating a self-securing loan structure.
Lenders assess equipment value based on:
- Current market value through industry guides and recent sales
- Condition and age affecting depreciation rates
- Specialized vs. general use impacting resale potential
- Maintenance records demonstrating care and longevity
Advance rates for equipment typically range from 50% to 80% of fair market value, with newer, general-purpose equipment commanding higher percentages.
Inventory and Receivables
Working capital lenders frequently accept inventory and accounts receivable as collateral. These current assets provide flexible security for businesses with strong sales cycles but limited fixed assets.
| Asset Type | Typical Advance Rate | Key Considerations |
|---|---|---|
| Accounts Receivable | 70-85% | Age, customer creditworthiness, concentration |
| Finished Goods Inventory | 50-70% | Shelf life, marketability, turnover rate |
| Raw Materials | 40-60% | Commodity vs. specialized, storage requirements |
| Work-in-Progress | 20-50% | Completion stage, transferability |
Asset-based lending structures built on receivables and inventory require regular monitoring, with advance rates adjusted based on aging reports and inventory counts.
Cash Assets and Investments
Liquid assets represent the most secure form of business loan collateral from a lender's perspective. Cash deposits, certificates of deposit, money market accounts, marketable securities, and bonds can secure loans at advance rates approaching 90% to 100% of value.
Some lenders offer cash-secured loans or securities-backed lines of credit with interest rates only slightly above the risk-free rate, since the collateral eliminates virtually all default risk.
Intellectual Property and Intangibles
Patents, trademarks, copyrights, customer lists, and proprietary technology can serve as collateral, though lenders approach these assets cautiously. Valuation challenges and liquidation difficulties limit their use to specialized lenders or situations where other collateral supplements the security package.
How Lenders Evaluate and Value Collateral
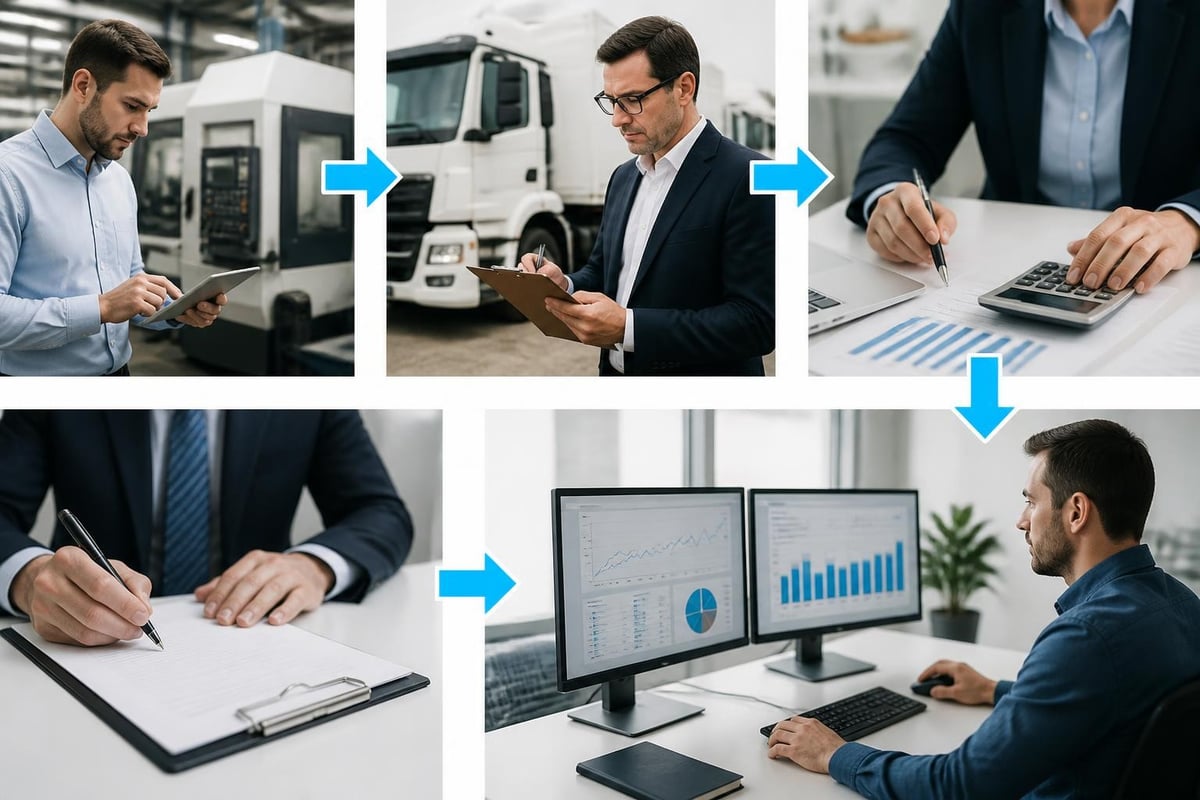
The collateral evaluation process determines how much a lender will advance against pledged assets. Professional appraisals, market analysis, and regulatory requirements all shape this assessment.
Loan-to-Value Ratios
Loan-to-value (LTV) ratios express the relationship between the loan amount and the collateral's appraised value. A $500,000 loan secured by property appraised at $1,000,000 represents a 50% LTV ratio. Lower ratios provide greater lender protection and typically result in better terms for borrowers.
Understanding collateral requirements helps business owners prepare appropriate documentation and select assets that maximize their borrowing capacity.
Conservative LTV ratios account for potential value decline, liquidation costs, and market volatility. Real estate might support 80% LTV, while inventory rarely exceeds 60% due to obsolescence risk and forced-sale discounts.
Appraisal and Valuation Methods
Lenders require professional appraisals for significant collateral, particularly real estate and specialized equipment. Appraisers consider:
- Comparable sales data from recent transactions
- Replacement cost for unique or specialized assets
- Income approach for income-producing property
- Forced liquidation value representing quick-sale scenarios
Regulatory guidance requires lenders to obtain independent appraisals for real estate collateral when loan amounts exceed certain thresholds. The appraisal must reflect current market conditions and be updated periodically for long-term loans.
Lien Priority and Position
When multiple creditors claim security interests in the same assets, lien priority determines who gets paid first in default situations. First-position liens carry the least risk and command the best terms. Second or subordinate liens face greater loss exposure and typically charge higher rates.
Before accepting collateral, lenders search public records to identify existing liens through:
- UCC financing statement searches for personal property
- Title searches for real estate
- Vehicle title records for automobiles and trucks
- Patent and trademark databases for intellectual property
Businesses with existing secured debt may struggle to pledge already-encumbered assets unless subordination agreements can be negotiated.
Collateral Requirements Across Loan Types
Different financing products carry varying collateral expectations based on risk profiles, loan purposes, and lender types.
Traditional Bank Loans
Commercial banks typically require substantial business loan collateral for term loans and lines of credit. Banks operate under strict regulatory oversight that mandates conservative lending practices and careful collateral documentation.
For loans exceeding certain thresholds, banks generally require collateral coverage at 100% to 150% of the loan amount, depending on asset quality. SBA-guaranteed loans follow specific collateral policies, requiring lenders to use available collateral but not declining otherwise creditworthy borrowers solely due to collateral shortfalls on loans under $350,000.
Asset-Based Lending
Asset-based lenders specialize in loans secured by current assets like receivables and inventory. These facilities provide working capital financing tied directly to asset values, with borrowing bases that fluctuate as collateral levels change.
Asset-based lending features include:
- Borrowing bases calculated from eligible receivables and inventory
- Regular field examinations and audits to verify collateral
- Advance rates that adjust based on concentration, aging, and quality
- Covenants that trigger if asset levels fall below minimums
This structure suits businesses with significant current assets but limited fixed property or credit challenges that prevent traditional financing.
Equipment Financing
Equipment loans and leases use the financed equipment as primary collateral. Since the lender's security interest attaches directly to the purchased asset, these loans often require minimal additional collateral.
Lenders may require personal guarantees or supplemental security if equipment values don't fully cover the loan amount, particularly for specialized machinery with limited resale markets.
Alternative and Revenue-Based Financing
Alternative lenders often minimize or eliminate traditional collateral requirements, focusing instead on business performance, revenue trends, and cash flow analysis. Merchant cash advances, revenue-based financing, and some online lenders use blanket liens or general security interests rather than specific asset pledges.
While these products may not require traditional business loan collateral, they typically carry higher costs that reflect the increased lender risk. Personal guarantees remain common even when specific asset collateral isn't required.
Strategies for Businesses Without Sufficient Collateral
Many growing businesses lack the hard assets traditional lenders prefer but still need capital to expand operations.
Building Collateral Over Time
Strategic asset acquisition can strengthen a business's collateral position. Purchasing equipment, building inventory, or acquiring real estate gradually creates pledgeable assets that support future borrowing.
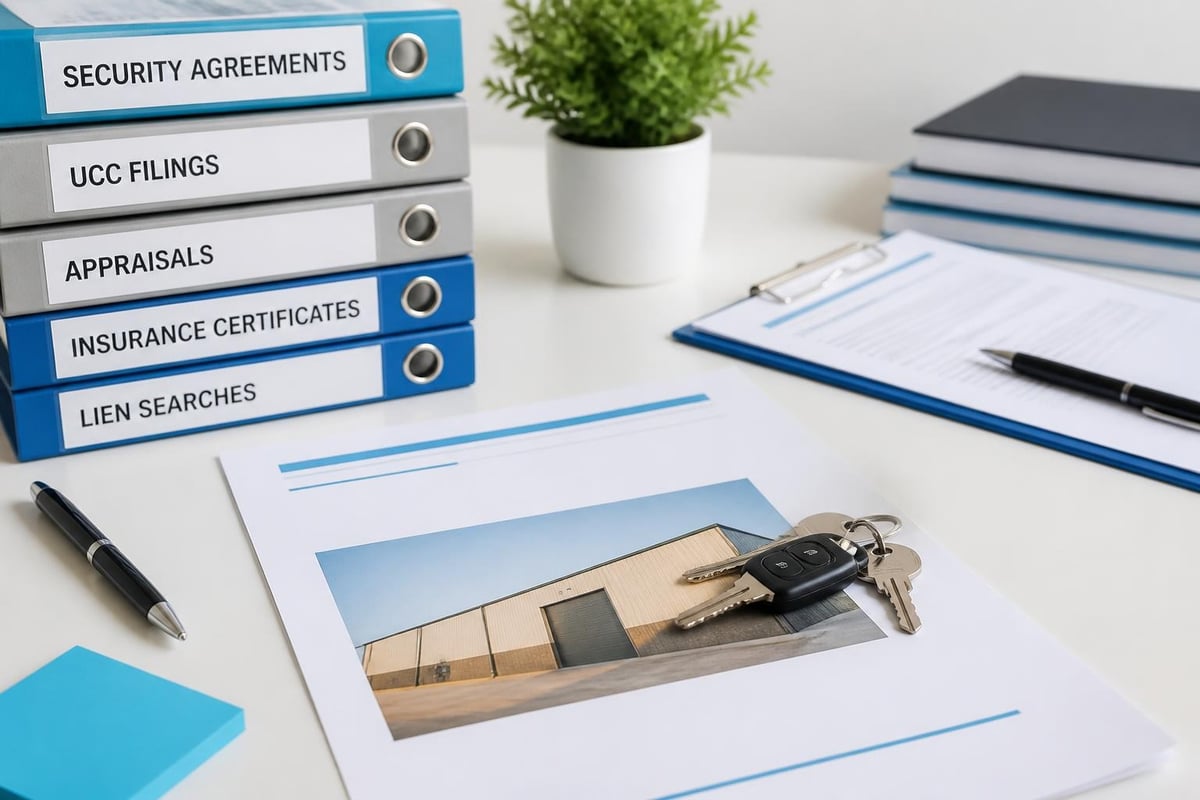
Businesses should maintain detailed records of asset purchases, including receipts, appraisals, and maintenance logs. Documentation demonstrates value and helps lenders evaluate collateral quickly.
Alternative Collateral Approaches
When traditional assets fall short, creative collateral arrangements may fill the gap:
- Cross-collateralization pledges assets from multiple related entities
- Blanket liens provide lenders with claims against all business assets
- Personal guarantees backed by personal assets supplement business collateral
- Third-party guarantees from investors or partners strengthen applications
Some businesses negotiate with vendors or customers to create secured positions in favorable contracts, purchase orders, or long-term agreements that demonstrate stable future cash flows.
Unsecured Financing Options
Creditworthy businesses with strong revenue and profitability may qualify for unsecured financing based on business performance alone. While interest rates typically run higher than secured loans, unsecured options preserve assets for operations or future secured borrowing.
| Financing Type | Collateral Required | Primary Qualification Factors |
|---|---|---|
| Traditional Bank Loan | High | Credit, collateral, cash flow |
| SBA 7(a) Loan | Moderate | Credit, business plan, available assets |
| Equipment Financing | Specific (equipment) | Equipment value, business stability |
| Revenue-Based Financing | Low/None | Monthly revenue, business performance |
| Unsecured Line of Credit | None | Credit score, time in business, profitability |
Legal and Regulatory Considerations
Collateral arrangements create legal obligations and risks that borrowers must understand before signing agreements.
Security Agreements and Documentation
Secured loans require extensive documentation establishing the lender's rights. The security agreement details pledged assets, borrower obligations, default conditions, and remedies available to the lender.
For personal property, lenders file UCC-1 financing statements with state authorities, creating public notice of their security interest. Real estate requires mortgages or deeds of trust recorded in county land records.
Borrowers should carefully review:
- Collateral descriptions ensuring accuracy and completeness
- Default definitions understanding what triggers lender rights
- Cross-default provisions that tie multiple obligations together
- Remedies and processes for collateral liquidation
- Personal liability beyond the pledged collateral
Default and Repossession Rights
When borrowers default, lenders can exercise their security interests through repossession and sale of collateral. State laws govern this process, requiring lenders to act commercially reasonably and often providing borrowers with notice and cure periods.
After liquidating collateral, lenders apply proceeds to outstanding loan balances, accrued interest, and collection costs. If proceeds fall short of amounts owed, lenders may pursue deficiency judgments against borrowers for the difference. Conversely, any surplus after paying secured debts returns to the borrower.
Regulatory Oversight
Banking regulators monitor how financial institutions manage collateral-dependent loans. Federal examination guidelines require banks to obtain current appraisals, document collateral value, and monitor collateral condition throughout the loan term.
These regulatory requirements protect both lenders and borrowers by ensuring realistic valuations and appropriate loan structures. Businesses benefit when lenders follow sound collateral practices that prevent over-leveraging and promote sustainable debt levels.
Maximizing Your Collateral Position
Business owners can take proactive steps to strengthen their collateral profile and improve financing opportunities.
Maintaining Asset Value
Regular maintenance, proper storage, and strategic upgrades preserve and enhance collateral value. Equipment service records, property improvements, and inventory management systems all demonstrate responsible asset stewardship that lenders appreciate.
Insurance coverage protects both borrower and lender interests. Lenders require borrowers to maintain adequate insurance on pledged assets, often naming the lender as loss payee or additional insured.
Strategic Asset Selection
Not all assets provide equal collateral value. When businesses have choices about which assets to pledge, consider:
- Liquidity determining how quickly assets convert to cash
- Marketability affecting the pool of potential buyers
- Appreciation potential for assets that may gain value
- Operational necessity balancing security needs with business use
Pledging non-critical assets preserves operational flexibility while providing lenders with security. Reserve essential equipment or facilities for later borrowing needs.
Professional Guidance
Working with experienced financing professionals helps businesses identify optimal collateral strategies. Business financing brokers understand lender requirements across multiple funding sources and can match borrowers with lenders whose collateral preferences align with available assets.
Financial advisors and attorneys ensure that collateral pledges serve business interests while meeting lender expectations. Professional guidance proves especially valuable when navigating complex situations involving multiple creditors, cross-collateralization, or specialized assets.
Industry-Specific Collateral Considerations
Different industries present unique collateral challenges and opportunities that shape financing approaches.
Manufacturing and Distribution
Manufacturers typically possess substantial equipment, inventory, and receivables that support diverse financing structures. However, specialized machinery may have limited resale markets, affecting advance rates and lender interest.
Distribution businesses benefit from high inventory turnover but face obsolescence risks that concern lenders. First-in-first-out inventory management and strong vendor relationships help mitigate these concerns.
Professional Services
Service businesses often lack traditional hard assets, relying instead on intellectual property, client relationships, and talented staff. These intangible assets rarely qualify as primary business loan collateral, pushing service firms toward unsecured financing or personal asset pledges.
Recurring revenue contracts and subscription models can strengthen applications by demonstrating predictable cash flow that reduces collateral dependence.
Retail and Hospitality
Retailers pledge inventory, fixtures, and sometimes real estate. Seasonal inventory swings require flexible borrowing structures that accommodate fluctuating collateral values.
Restaurants and hotels combine real estate, equipment, and furnishings to create collateral packages. Location-specific assets may present liquidation challenges that affect lender appetite and advance rates.
Healthcare and Medical Practices
Medical equipment, from imaging machines to surgical instruments, provides strong collateral due to consistent demand and established secondary markets. Receivables from insurance companies and government programs offer additional security, though reimbursement complexity sometimes concerns lenders.
Regulatory licensing requirements and specialized facility needs can both help and hinder collateral positions depending on market conditions.
Current Trends in Business Loan Collateral
The collateral landscape continues evolving as lending practices, regulations, and business models change.
Technology and Digital Assets
Emerging asset classes challenge traditional collateral frameworks. Software, databases, digital content, and cryptocurrency present valuation and enforcement difficulties but represent significant business value.
Recent regulatory guidance addresses how lenders should approach venture lending collateral, including intellectual property and technology assets. As markets mature, expect more sophisticated valuation methods and lending products built around digital assets.
Environmental and Social Considerations
Environmental factors increasingly influence collateral value, particularly for real estate and manufacturing facilities. Properties with environmental contamination or climate risk exposure may see reduced advance rates or require additional protections.
Lenders also consider sustainability certifications and energy-efficient improvements as value-enhancing factors that strengthen collateral positions.
Economic Factors
Macroeconomic conditions affect collateral use patterns, with secured lending typically increasing during uncertain periods. Interest rate environments, real estate market conditions, and commodity price volatility all impact how lenders view various asset classes.
Business owners should monitor these trends and adjust collateral strategies accordingly, refinancing when conditions favor their asset mix and preserving flexibility during volatile periods.
Understanding business loan collateral empowers you to approach financing strategically, whether you're securing your first business loan or optimizing existing debt structures. The right collateral approach balances lender requirements with operational needs, preserving flexibility while unlocking capital for growth. Enterprise Finest Solutions helps small and medium-sized businesses navigate the complex landscape of secured and alternative financing, connecting you with funding partners whose collateral requirements align with your available assets and business goals. Explore how Enterprise Finest Solutions can help you identify the right financing structure for your situation and secure capital that supports your business vision.
Written by
Enterprise Finest Solutions
Content creator and writer sharing insights and stories.


